
Key points:
-
Depreciation of the dollar against the euro
-
Resumption of attacks by Ukraine on theUkraine of Russian energy infrastructure
-
Comfortable global grain production confirmed by the International Grains Council but trade is contracting
-
Corn is driving Ukraine’s grain exportsUkraine but millions of tonnes still in the fields
The prices of wheat and corn were falling this Thursday, both on the CBOT and on Euronext.The U.S. dollar’s retreat after its recent peak is nevertheless supporting markets. The resumption of Ukrainian attacks on energy infrastructure, announced by Volodymyr Zelensky is also fueling geopolitical uncertainty.
Wheat prices fall on the CBOT
Wheat priceswheat on the CBOT were down this Thursday. They were losing 2 to 5 cents per bushel, depending on the delivery month. The market nevertheless remains supported by tensions in the Black Sea and concerns about winter crops in several producing regions. Drought in southern Russia and difficulties establishing winter wheat in the United States remain under close watch.
For the December 2026 contract, the most actively traded, wheat was losing 3,25 cents per bushel at 670 cents. The March 2027 contract was down 2,25 cents at 684,25 cents per bushel.
IGC raises global grain harvest forecast, but trade continues to slow
The IGC raised its global production forecast by 7 Mt for cereals (wheat and coarse grains) for 2026-2027, now estimated at 2,427 billion tonnes. This revision is mainly due to better prospects for corn as well as a positive revision for barley.
World consumption is expected to reach 2,446 billion tonnes, a new record driven by food and industrial demand.
World ending stocks have also been revised upward. They are up by 11 Mt compared with the previous report, reaching 619 Mt. Despite this revision, they would remain 19 Mt below those of 2025-2026 and at their lowest level in several seasons.
This increase is largely attributable to corn, whose ending stocks are now estimated at 297 Mt compared with 289 Mt in the September report.
World trade in cereals is now expected at 450 Mt, or 1 Mt less than in the September report and 17 Mt less than in the previous season. The corn therefore remains the only major cereal whose trade is increasing significantly, at 209 Mt.
Le Wheat prices edge slightly lower on Euronext
Following the prices recorded on the CBOT, the prices of wheat on Euronext fell by 0,5 to nearly 4 €/t depending on the maturities.
For the December 2026 contract, wheat fell by 2 €/t to 246,25 €/t, while the March 2027 contract declined by 1 €/t to 247 €/t.
To find out all the latest news on agricultural markets, click here
After falling below 1,12 dollars for several days, the euro slightly strengthened against the greenback this Thursday. It was trading at 1 1219 dollars against 1 1157 dollars the day before. This morning at 6 h 30 (Paris time), theeuro was still progressing at 1,1231 dollars.
Regarding the wheat, Expana maintains its European production forecast at 126,1 Mt for 2026-2027, a volume 8 % lower than that of the previous crop year.
Corn prices continue to fall in Chicago
The price of corn in Chicago CBOT were trending lower again this Thursday. They were down 1 to 4 cents per bushel, depending on the contract month. The market continues to come under pressure from the U.S. harvest, while remaining supported by the competitiveness of U.S. exports.
For the December 2026 contract, the most actively traded, the corn was losing 2,75 cents per bushel to 478 cents. For March 2027, it was down 3,25 cents to 491 cents per bushel.
The prices of corn also moved in line with the oil market, which fell again on Thursday. The Brent December contract was down 0,40 % at 105,69 $/barrel on Thursday, while the WTI November futures gained 2,50% to 97,56 $/barrel. The U.S. crude market remained supported by strong demand as commercial inventories fell by 8,6 million barrels, according to theEnergy Information Administration. This Friday morning at 6 h 35 (Paris time), the Brent fell by 0,44% and the WTI by 0,35%.
Two oil tankers caught fire during the night of 15 October near the Sulina Canal, in Romanian territorial waters, while Romanian authorities reported new incursions by Russian drones into their airspace. This canal is one of the main export corridors for Ukrainian grain.
In Argentina, the sowings of grain maize have reached 34,8% of the 8,4 million hectares planned, about five percentage points ahead of the previous season. However, rainfall in recent days has slowed planting in the center and south of the country.
In Brazil, the Conab estimates corn production at 148 Mt, supported by strong demand from the ethanol and animal feed sectors.
Ukraine: millions of tonnes of corn still in the fields after heavy rains
Persistent rains in Ukraine are severely disrupting the harvest of corn and increase production costs. With high grain moisture, additional drying costs are estimated at between 10 and 20 $/t, potentially reaching 30 $/t in some cases. This situation significantly reduces producers’ profitability amid already depressed prices.
To date, only 3,5 Mt of corn have been harvested, while approximately 25 to 27 Mt remain in the fields. Poor weather conditions could extend the harvest into winter.
Analysts ate PUSK, the market analysis center of the Ukrainian Agri Council (UAC), also consider the USDA forecast of USDA projecting 22 Mt of Ukrainian corn exports too optimistic. They estimate the actual potential at between 17 and 19 Mt. Between November and March, the’Ukraine and the United States should nevertheless remain the main suppliers to the global market.
According to PUSK, Ukrainian export infrastructure currently allows about 1,5 Mt of corn to be shipped per month.
European corn falls on Euronext
After its sharp rise the previous day to above 300 €/t, the corn was declining on EuronextLosses ranged from 1 to 13 €/t depending on the delivery months.
For the November 2026 delivery month, the second most traded delivery month after March, corn was down 1,75 €/t to 301,25 €/t. For March 2027, it fell by 5 €/t to 275,75 €/t. For May 2027, it lost 4,75 €/t to 272,25 €/t.
The analytics firm Expanhas lowered its production forecast for corn of theEuropean Union for the 2026-2027 campaign at 44,9 Mt, compared with 46,2 Mt estimated in September. If this estimate is confirmed, the European harvest would reach its lowest level since 1990. Expana also estimates that the use of corn in rations could decline by 8 Mt, or 13,5% compared with the average of the past five years.
Corn becomes the driver of Ukrainian grain exports
While total exports of cereals and pulses from Ukrainefell sharply in 2026-2027, while corn was an exception and supported the country’s exportable supplies.
On 14 October, Ukraine had exported more than 2 Mt of corn, representing a year-on-year increase of 76%. The price gap remains spectacular:
-
The Ukrainian corn FOB is approximately 120 €/t cheaper than the French corn FOB.
-
The differential with the German corn reaches nearly 140 €/t.
Stay up to date in real time!
Follow topics, legislative projects, companies, and public figures to be notified as soon as we publish an article.
orgeFollow-upFollowforward marketTrackingFollow
This discount allows theUkraine to preserve its market outlets despite logistical difficulties.
FUNDAMENTALS – campaign 2026-2027
Production, European Union, corn : 44,9 %Mt versus 46,2 Mt previously estimated (Source: Expana)
Export, Ukraine, corn : from 17 to 19 Mt (Source: PUSK)
Production, World, cereals : 2427 Mt compared with 2420 Mt estimated as of 17/09 (Source: CIC)
Production, World, corn: 1307 Mt versus 1301 Mt estimated as of 17/09 (Source: CIC)
Consumption, World, cereals : 2444 Mt versus 2447 Mt estimated as of 17/09 (Source: CIC)
Consumption, World, corn : 1323 Mt versus 1321 Mt estimated as of 17/09 (Source: CIC)
Ending stocks, World, cereals : 619 Mt compared with 608 Mt estimated as of 17/09 (Source: CIC)
Ending stocks, World, corn : 297 Mt compared with 289 Mt estimated as of 17/09 (Source: CIC)
Production, Brazil, corn : 148 Mt, + 2,4 % compared with 2025-2026 (Source: Conab)
Area, Brazil, corn : 23,7 Mha, + 4 ?9 % compared with 2025-2026 (Source: Conab)
Production, Brazil, wheat : 5,7 Mt, - 27 % compared with 2025-2026 (Source: Conab)
INTERNATIONAL TRADE
Trade, World, cereals : 450 Mt versus 451 Mt estimated as of 17/09 (Source: CIC)
(week 15 ending on 11 October 2026)
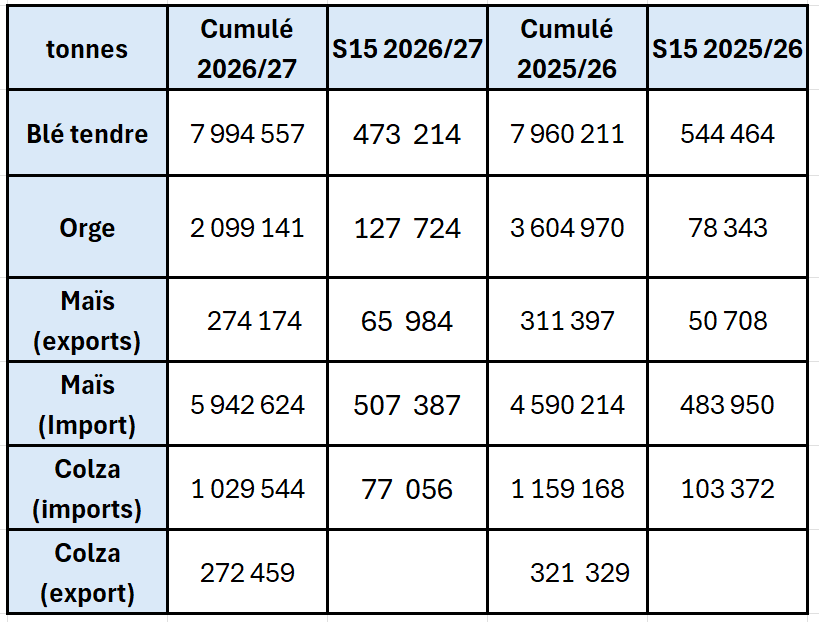
French physical markets from 15 October 2026 (July basis for cereals)
| Soft wheat | Specifications | Expiry | euro/t | Variation | |
|---|---|---|---|---|---|
| Dunkirk output | 220/11 meunier Harvest 2026 | Oct.–Dec. | 245,00 | N | -2,00 |
| Rendu La Pallice | 76/220/11 Harvest 2026 | Oct.–Dec. | 249,00 | N | -2,00 |
| Rendu Rouen | 76/220/11 Harvest 2026 | Oct.-Dec. | 245,50 | N | -2,00 |
| Pontivy/Guingamp yield | forage 74 kg/hl base, 72 kg/hl mini Harvest 2026 | Oct.–Dec. | 252,50 | N | -2,00 |
| Fob Moselle | Meunier Harvest 2026 | Oct.–Dec. | 223,50 | N | -2,00 |
| Fob Rouen | Higher FCW A2 class 1 major included Harvest 2026 | Oct. | 254,99 | N | |
| Fob La Pallice | FAW Superior A2 class 1 maj. included Harvest 2026 | Oct. | 258,29 | ||
| Marne Departure | BPMF 220 Hagberg Harvest 2026 | Oct.–Dec. | 235,50 | N | -2,00 |
| Start Eure/Eure-et-Loir | BPMF 76 kg/hl Harvest 2026 | Oct.–Dec. | 237,50 | N | -2,00 |
| Southeast departure | harvester miller 2026 | Oct.–Dec. | 249,50 | N | 0,00 |
| Corn | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Bordeaux rendering | Harvest 2026 | Oct.–Dec. | inc. | ||
| Rendu La Pallice | Harvest 2026 | Oct.–Dec. | inc. | ||
| Pontivy/Guingamp rendering | Harvest 2026 | Oct.–Dec. | 324,50 | N | -2,00 |
| Fob Bordeaux | Harvest 2026 | Oct.–Dec. | inc. | ||
| Fob Rhin | Harvest 2026 | Oct.–Dec. | 278,00 | N | -2,00 |
| Harvest 2026 | Jan.-June | 276,00 | N | -5,00 | |
| Southeast departure | Harvest 2026 | Oct.–Dec. | inc. |
| Durum wheat | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Port-la-Nouvelle rendering | Semolina standards Harvest 2026 | Oct.–Dec. | 305,00 | N | 0,00 |
| Starting point Eure/Eure-et-Loir | seed standards Harvest 2026 | Oct.–Dec. | 290,00 | N | 0,00 |
| Southeast departure | Semolina standards Harvest 2026 | Oct.–Dec. | 290,00 | T | 0,00 |
| Forage barley | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Rendu Rouen | 62-63 kg/hl Harvest 2026 | Oct.–Dec. | 220,50 | N | -2,00 |
| Rendu Pontivy/Guingamp | Harvest 2026 | Oct.–Dec. | 234,50-236,50 | N | -2,00 |
| Fob Moselle | without limit. d'orgettes Harvest 2026 | Oct.–Dec. | 206,50 | N | -2,00 |
| Departure Eure/Eure-et-Loir | Harvest 2026 | Oct.–Dec. | 212,50 | N | -2,00 |
| Southeast departure | 65-67 kg/hl Harvest 2026 | Oct.-Dec. | 228,00 | N | 0,00 |
| Brewing barley - Winter 6 rows | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Fob Creil | Faro 11,5% max Port 500 t Harvest 2026 | Jan.-June | 220,00-221,00 | N | 0,00 |
| Brewing barley - Spring | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Fob Creil | Planet 11,5% max Port 500 t Harvest 2026 | Jan.-June | 239,00 | N | 0,00 |
| Weight | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Marne departure | Forage harvest 2026 | Oct.–Dec. | 270,00-275,00 | N | 0,00 |
| Somme/Oise departure | Forage harvest 2026 | Oct.–Dec. | 276,00-281,00 | N | 0,00 |
Quotations for milling by-products on 13 October 2026
| Fine soft wheat bran | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 179,00-181,00 | T | 2,00 | |
| pellets | dispo. | 199,00-201,00 | T | 5,00 |
| Semi-white regrinding | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 199,00-201,00 | T | 5,00 |
| Low-protein soft wheat flour | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 204,00-206,00 | T | 5,00 |
| Durum wheat porridge | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 204,00-206,00 | T | 5,00 |
Dairy product market quotations of 8 October 2026
| Milk powder | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| NBPL departure in 30 days 5% H BT bulk | Available. | 3275,00 | N | 0,00 |
| Whey powder | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| NBPL departure in 30 days, BILA pH 6 bulk | Available. | 1650,00 | T | -30,00 |
| Buttermilk | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| without a standard | available. | n.p. | |||
| Dutch standards | available. | n.p. |
Dollar / euro exchange rate of 15 October 2026
| Currency | Value at closing |
|---|---|
| 1 US dollar | 0,8922 euro |
| 1 euro | 1,1208 dollars |
Chicago futures market close on 15 October 2026
| Raw materials | Closure | Chicago |
|---|---|---|
| Wheat | 670,00 | cents/wood. |
| Corn | 478,00 | Cents/wood. |
| Ethanol | 2,161 | $/gallon |
Euronext futures market close on 15 October 2026
| Milling wheat (Euronext) | |
|---|---|
| Deadline | Closing |
| Dec. 2026 | 246,25 |
| Mars 2027 | 247,00 |
| Mai 2027 | 245,75 |
| Volume | 98483 |
| Maize (Euronext) | |
|---|---|
| Maturity | Closing |
| Nov. 2026 | 301,25 |
| Mars 2027 | 275,75 |
| June 2027 | 272,25 |
| Volume | 4111 |
International market quotations for 15 October 2026
| Energy | Deadline | Closing value |
|---|---|---|
| Oil (Nymex) | Nov. 2026 | 97,97 $ |
| Maritime freight indices | of 14 October | Variation |
|---|---|---|
| Baltic Dry Index (BDI) | 2667 | -134,00 |
| Baltic Panamax Index (BPI) | 2409 | -23,00 |
| Baltic Capesize Index (BCI) | 3630 | -364,00 |
| Baltic Supramax Index (BSI) | 1845 | 12,00 |
| Baltic Handysize Index (BHSI) | 1003 | 3,00 |