Key points:
-
U.S.-origin soybeans are still awaiting Chinese purchases
-
Soybean harvest conditions are not weighing on prices
-
In France, Agreste has updated its production forecasts for rapeseed, sunflower and soybeans
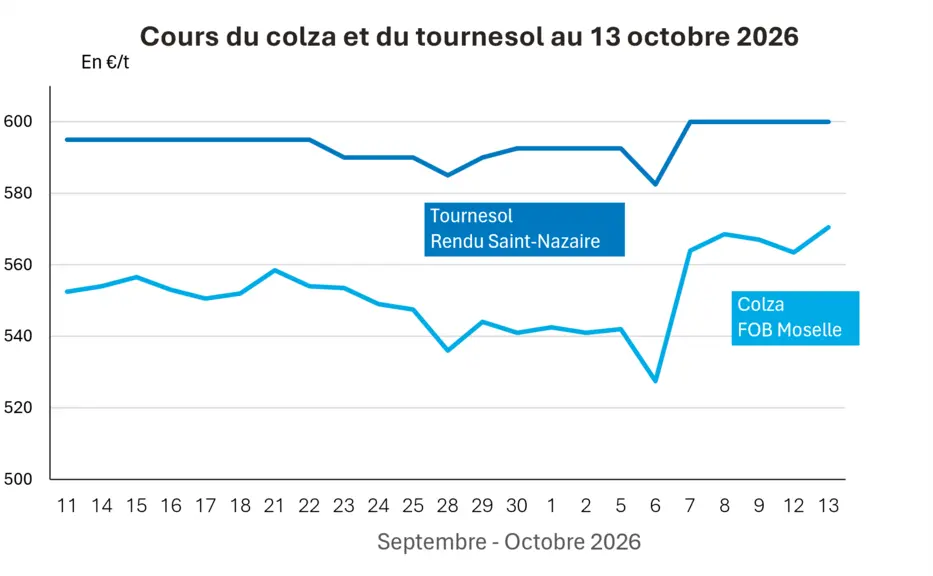
Soybean prices on the Cbot fell this Tuesday, 13 October 2026: - 4 cts$/bu, to 1 283,75 cts$/bu, for the most-traded November 2026 contract, and – 4,75 cts$/bu, to 1 300 cts$/bu, for the second most active January 2027 contract. The March 2027 contract, the third most active, closed down 6 cts$/bu, at 1 308,50 cts$/bu. The decline applied to all maturities open for trading and was steeper for terms from March 2027 to August 2027 (from – 5,75 to – 6,25 cts$/bu). On Euronext, rapeseed prices rose quite sharply: + 7 €/t, to 559,25 €/t, for the most-traded February 2027 contract, and + 7 €/t also for the second most active February 2027 contract. The rise applied to all maturities open for trading and was more pronounced for terms from February 2027 to February 2028. The nearest November 2026 contract closed up 1,75 €/t, at 518,75 €/t (trading ended on 31 October). The Fob Moselle rapeseed, the benchmark in France’s physical markets, also gained ground, at 570,50 €/t (+ 7 €/t).
Soybean pricessoybeansCbot corn saw a session driven by technical selling and fund selling. The weekly publication of the Crop Progress report this Tuesday (instead of Monday due to Columbus Day) did not necessarily affect traders’ activities, with the harvest progressing but still under pressure due to new rains expected this week (Midwest and Plains) and plant health unchanged from one week to the next. All this against a backdrop of soil moisture also remaining almost unchanged. However, the November contract reached an intraday high at 1 281,50 cts$/bu, very close to 1 280 cts$/bu, while the January contract 2027 reached a low of 1 297,75 cts$/bu, below the 1 300 cts$/bu level. Furthermore, the export inspections of the week, published by the USDA, came in below analysts’ expectations (with China and Mexico as the main destinations). Market participants are still waiting for Chinese buyers to return, a wait that is starting to feel a little long, according to some market observers.
Prices for soybean meal and soybean oil fell on Tuesday in U.S. markets.
Internationally, planting in Brazil are progressing well despite the recent floods in the south of the country, ahead of last year according to some brokers (planting completed at around 40%). Casde, the Chinese equivalent of the Wasde in the United States, but applicable to China, reports a possible decline in soybean production in 2026/2027 in China of 590 000 t, to 20,36 Mt (October forecast compared with September), due to a slightly smaller planted area and slightly lower yields. Import forecasts remain unchanged at 95,5 Mt and domestic crushing at 94 Mt.
In rapeseed, prices therefore rose on Euronext for the second consecutive session, mainly on technical considerations and following Tuesday’s rise in oil prices. Crude oil rose under the combined influence of an increase in attacks on ships in the Black Sea (off the coast of Bulgaria this time) and attacks by the Houthis in Yemen.
The canolaThe side quoted in Winnipeg instead gave up ground this Tuesday, across all the maturities offered for trading.
Prices for high-oleic sunflower delivered Saint-Nazaire were unchanged from one session to the next. In Ukraine, the inability to ship the volumes of sunflower oil already produced in for logistical reasons due to the war with Russia is starting to cause problems for crushers: oil storage capacity is being used almost to its maximum, and it is becoming difficult to store the new volumes produced, prompting some operators to significantly reduce or even halt production. This could also lead to a deterioration in the quality of seeds awaiting crushing, according to UkrOliyaProm.
Fundamentals :
France, rapeseed, production : estimated at 4,736 Mt in October for 2026/2027, compared with 4,743 Mt in September, but an increase of 1,7 % compared with the 2025/2026 production and + 14,4 % compared with the five-year average (source: Agreste)
France, sunflower, production : estimated at 1,216 Mt in October for 2026/2027 versus 1,311 Mt in September, a decrease of 14,2% compared with 2025/2026 and – 29,9% compared with the five-year average (source: Agreste)
France, soybeans, production : estimated at 281 000 t in October for 2026/2027 versus 298 000 t in September, a decrease of 29,3% compared with the 2025/2026 marketing year and – 29,7% compared with the five-year average (source: Agreste)
United States, soybeans, harvest : 46 % completed as of 11 October 2026 versus 25 % last week and 50 % five-year average (source: USDA)
United States, soybeans, crop conditions : 57 % good to excellent as of 11 October 2026, unchanged from last week (source: USDA)
Stay informed in real time!
Follow topics, legislative projects, companies, and public figures to be notified as soon as we publish an article.
futures market
Following
Follow
French physical market quotations as of 13 October 2026 July base for cereals
|
Sunflower
|
Specifications
|
Deadline
|
euro/t
|
|
|
Bordeaux rendering
|
oleic Harvest 2026
|
Oct.–Dec.
|
605,00
|
N
|
|
Saint-Nazaire rendering
|
oleic Harvest 2026
|
Oct.–Dec.
|
600,00
|
N
|
|
Rapeseed
|
Specifications
|
Deadline
|
euro/t
|
|
|
Rouen delivery
|
Harvest 2026
|
Jan.–Mar.
|
561,50
|
N
|
|
Fob Moselle
|
Harvest 2026
|
Jan.–Mar.
|
569,50-571,50
|
N
|
|
Soybean meal
|
Specifications
|
Deadline
|
euro/t
|
|
|
Departure from Montoir
|
48% protein pellets Brazil
|
Oct.
|
Inc.
|
|
|
|
48% protein pellets Brazil
|
Nov.
|
466,00
|
V
|
|
|
48% profat pellets Brazil
|
Dec.
|
467,00
|
V
|
|
Pois
|
Specifications
|
Deadline
|
euro/t
|
|
|
Marne departure
|
forage Harvest 2026
|
Oct.–Dec.
|
260,00
|
N
|
|
Somme/Oise departure
|
Forage harvest 2026
|
Oct.-Dec.
|
268,00
|
N
|
Commercial dairy product quotations of 8 October 2026
|
Products
|
Specifications
|
Deadline
|
euro/t
|
|
|
Milk powder
|
NBPL departure in 30 days 5% H BT bulk
|
available.
|
3275,00
|
N
|
|
Whey powder
|
NBPL departure in 30 days, BILA pH 6 bulk
|
available.
|
1650,00
|
T
|
|
Buttermilk
|
without a standard
|
available.
|
n.p.
|
|
|
|
Dutch standards
|
available.
|
n.p.
|
|
Rec.: Harvest; avail.: available; Inc.: incoterm; N: Nominal; T: Treated; V: Seller.
Dollar/euro exchange rate as of 13 October 2026
|
|
Futures market quotes, 13 October 2026
|
|
Currency
|
Value at closing
|
|
1 US dollar
|
0,8938 euro
|
|
1 euro
|
1,1188 dollars
|
|
|
|
Raw materials
|
Chicago close
|
Unit
|
|
Soy
|
1283,75
|
cts/wood.
|
|
Soybean meal
|
370,10
|
$/t
|
|
Soybean oil
|
67,67
|
cts/livre
|
bu.: bushel.
|
European futures markets close on 13 October 2026
|
|
|
|
|
Colza Euronext
|
|
Deadline
|
Closing
|
|
Nov. 2026
|
518,75
|
|
Feb. 2027
|
559,25
|
|
May 2027
|
563,50
|
|
Volume
|
23237
|
|
|
|
UAN30 nitrogen fertilizers Euronext
|
|
Deadline
|
Closing
|
|
March 2022
|
157,00
|
|
June 2022
|
157,00
|
|
Sept. 2022
|
157,00
|
|
Volume
|
0
|
|
|
|
|
|
International market quotations as of 13 October 2026
|
Energy/Sugar
|
Maturity
|
Value at close
|
|
Oil (Nymex)
|
Nov. 2026
|
94,14 $
|
|
London sugar
|
Dec. 2026
|
561,90 $/t
|
|
New York sugar
|
March 2027
|
21,11 cts/pound
|
|
Ocean freight indices of October 12
|
|
Baltic Dry Index (BDI)
|
2852
|
|
Baltic Panamax Index (BPI)
|
2432
|
|
Baltic Capesize Index (BCI)
|
4148
|
|
Baltic Supramax Index (BSI)
|
1821
|
|
Baltic Handysize Index (BHSI)
|
998
|