Key points:
-
Delayed sowing of wheat in the United States
-
Massive imports of corn in the European Union
-
Return of Egypt to the market with strengthened quality criteria
-
Chinese demand for cornrevised downward
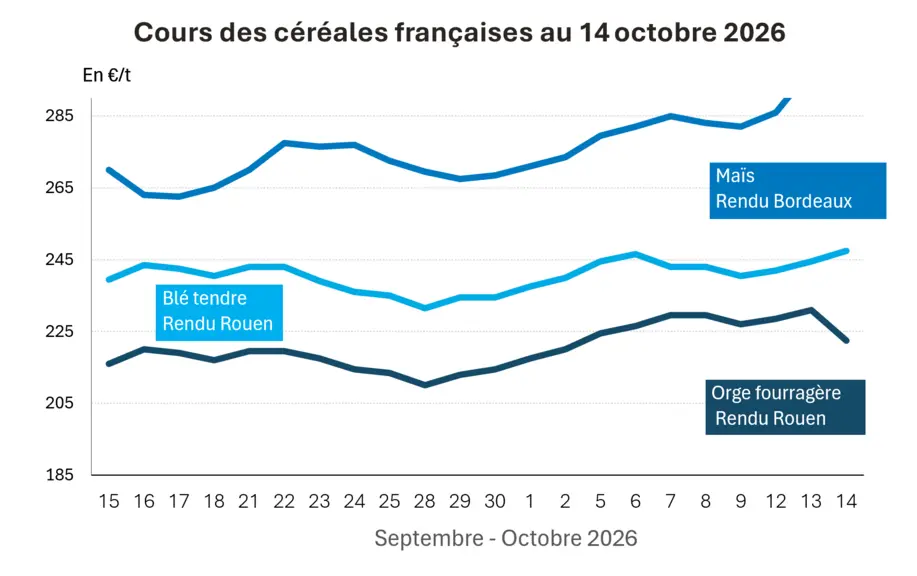
Wheat remains supported by delayed sowing in the United States, geopolitical tensions and Algerian purchases, although abundant global supplies are limiting price increases. Corn remains under pressure amid abundant supply in the United States. Prices remain divided, however, between the weakness of the euro, uncertainties in Ukraine and limited European availability.
Wheat prices extend their gains on the CBOT
Wheat prices wheat au CBOT moved in mixed directions this Wednesday depending on the contract month. Nearby contracts rose by 1 to 4 cents per bushel, while more distant contracts, beyond December 2027, fell by 1 to 2 cents per bushel.
For the December 2026 contract, the most actively traded, wheat gained 4 cents to reach 673,25 cents per bushel. The March 2027 contract also posted a gain of 3,25 cents to 686,5 cents per bushel.
Recent news concerning Starlink en Ukraine and a possible increase in intervention by the United States worry markets and support prices.
The market is now monitoring risks to the 2027 harvest. The report Crop Progress, published late due to Columbus Day, shows that planting of winter wheat U.S. were at 51% as of October 11, compared with 36% a week earlier, but remain 7 points below the five-year average. According to Joe Davis (Futures International), this delay increases the crop’s sensitivity to weather conditions in the coming weeks.
While many factors are bullish in the short term, the global wheat supply fundamentals recently published by the USDA nevertheless limit price gains.
Wheat prices edge up on Euronext
In the wake of the prices recorded on the CBOT, the prices of wheat on Euronext were rebounding and gaining 1 to nearly 3 €/t depending on the delivery dates.
For the December 2026 contract, the wheat rose from 2,50 €/t to 248,25 €/t, while the March 2027 contract gained 1,25 €/t to 248 €/t.
European prices for wheat are supported by the weakness of the euro, stronger import demand and concerns about Black Sea availability.
Click here to find out everything about the latest news in agricultural markets
The euro continued its decline against the dollar. The single currency was trading at 1,1157 $, compared with 1,1198 $ on Tuesday. However, this Thursday morning at 6 h 25 (Paris time), it had risen to 1,1226 $.
Funds increased their long position on the Matif of 12 000 lots, bringing their long position to 143 500 lots.
Internationally, Algeria reportedly purchased 750 000 tons of wheat at a price close to 326 $/t, mainly from the Baltic, from'South America and the Black Sea. Despite regaining competitiveness, French origin was once again ruled out.
Ukraine: winter cereal sowing is progressing faster than in 2025
As of 13 October, theUkraine had sown 3,39 million hectares of winter cereals, or 65,1 % of the national target of 5,21 million hectares.
On the same date last year, planted areas reached 3,10 Mha, or only 57,1 % of the program, demonstrating faster progress this season.
Egypt: toward stricter criteria for imported wheat ahead of a return to the market
TheEgypt plans to impose a minimum baking strength of W160 for its public purchases of wheat following several quality problems with Bulgarian cargoes, including a batch of 32 000 tonnes rejected by Mostakbal Misr.
This requirement would generally be compatible with French, Russian, Ukrainian and Romanian wheats, which usually meet this quality level. Some other origins could, however, be penalized.
This development could also reduce the number of offers eligible for Egyptian tenders, as the country is expected to return to the market shortly to replenish its stocks ahead of Ramadan 2027.
Corn prices fall in Chicago
The corn evolves in a different context from that of wheat. The upward revision to yields in the United States and the prospects of an abundant harvest limit the upside potential to Chicago.
Corn prices corn au CBOT fell again this Wednesday, losing up to 2 cents/bushel depending on the delivery month.
For the December 2026 contract, the most active, the price of corn was falling by 2 cents to 480,75 cents/bushel. For March 2027, it was down 2,25 cents to 494,25 cents/bushel.
Prices were moving in step with oil. The Brent December's deadline was falling by 0,19% to 106,09 $/barrel on Wednesday while the West Texas Intermediate (WTI)The November deadline was progressing from 0,45% to 95,18 $/barrel. The conflict between the Houthis and Saudi Arabia, as well as the attacks reported in the Strait of Hormuz, nevertheless continue to support oil prices at high levels. According to the prixdubaril.com website, at least ten vessels have reportedly been attacked in the strait since Sunday. A container ship reportedly struck a mine on Wednesday before sinking.
Furthermore, Donald Trump announced on Wednesday the launch of a large-scale oil and gas exploration campaign in Greenland, where significant hydrocarbon reserves may be present. . On Thursday morning at 6 h 45 (Paris time), oil markets were nevertheless correcting downward, Brent giving up 1,66 % and WTI 1,15 %.
The latest report Crop Progress confirms the delay in the harvest of corn in the United States. In October 11, 33% of the areas had been harvested, compared with 23% a week earlier and 39% on the five-year average. A harvest delay is also observed in Ukraine. Furthermore, the conditions of the cornRemaining to be harvested are improving, with 56% of the areas rated good to excellent, compared with 54% the previous week.
Operators are now awaiting the weekly U.S. export figures, whose release was postponed until Friday due to Columbus Day. Markets will pay particular attention to the pace of Mexican purchases, Asian demand, and competition from Brazilian corn.
China: sharp downward revision to corn demand for animal feed
In its October report (CASDE, the China has sharply lowered its consumption forecasts for corn for animal feed for the 2025/26 and 2026/27 seasons.
Consumption of corn in rations is now estimated at 200,5 Mt in 2026/27, or 9,1 Mt less than in the September forecasts. For 2025/26, the revision amounts to a downward adjustment of 9,4 Mt, to 201,5 Mt.
In total, Chinese consumption of corn for 2026/27 is reduced to 306,9 Mt from 311,7 Mt previously, while production remains estimated at 306 Mt and imports at 6 Mt.
This revision appears bearish for the global corn.The slowdown in Chinese demand reduces medium-term import prospects and reinforces the sense of abundant global supply.
European corn prices soar on Euronext
Prices of corn were sharply higher this Wednesday, gaining from 5 to 14 €/t depending on the delivery month.
For the November 2026 contract, the second most traded after March, the price of corn was up 14 €/t at 303 €/t. For March 2027, it gained 11 €/t to 280,75 €/t.
Following its Specialized Grain Council of 13 October, FranceAgriMer reviewed the final stock of corn in France at 1,1 Mt, compared with 1,5 Mt estimated in September. This downward revision is due to production and collection now estimated at 6,6 Mt and 6,2 Mt, respectively, or 700 000 tonnes less than the September forecasts.
Read also: French maize stocks at their lowest since 1990-1991, which could soon be revised downward, but comfortable reserves of straw cereals
Stay up to date in real time!
Follow topics, legislative projects, companies, and public figures to be notified as soon as we publish an article.
This stock could still be revised downward, and operators also expect the European Commission's corn balance sheet to be revised in the coming weeks.
European prices for corn remain supported by strong imports. These are up by 29 % compared with 2025 and have reached more than 5,9 Mt since July 1st, including 2,9 Mt destined for Spain.
If the United States are now the leading supplier of theEuropean Union, the Brazil ranks in second place, tied with Ukraine, each with a 25% market share.
Over the past fifteen days, European Union imported more than 300 000 tonnes of corn from Brazil, compared with only a little over 100 000 tonnes from'Ukraine. This trend illustrates the growing importance of Brazilian origin in European supply, while Ukrainian availability remains limited.
Weekly EU cereal and rapeseed exports/imports:
(week 15, ending 11 October 2026) - tonnes
| tonnes | Cumulative 2026/27 | S15 2026/27 | Cumulative 2025/26 | S15 2025/26 |
| Soft wheat | 7 994 557 | 473 214 | 7 960 211 | 544 464 |
| Orge | 2 099 141 | 127 724 | 3 604 970 | 78 343 |
| Corn (exports) | 274 174 | 65 984 | 311 397 | 50 708 |
| Corn (Import) | 5 942 624 | 507 387 | 4 590 214 | 483 950 |
| Colza (imports) | 1 029 544 | 77 056 | 1 159 168 | 103 372 |
| Colza (export) | 272 459 | 321 329 |
French physical markets from 14 October 2026 (July basis for cereals)
| Soft wheat | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Dunkirk rendering | 220/11 miller Harvest 2026 | Oct.–Dec. | 247,00 | T | 4,00 |
| La Pallice rendering | 76/220/11 Harvest 2026 | Oct.–Dec. | 251,00 | T | 4,50 |
| Rouen Rendering | 76/220/11 Harvest 2026 | Oct.–Dec. | 247,50 | T | 4,50 |
| Pontivy/Guingamp yield | Forage 74 kg/hl base, 72 kg/hl mini Harvest 2026 | Oct.–Dec. | 254,50 | T | 9,00 |
| Fob Moselle | meunier Récolte 2026 | Oct.–Dec. | 225,50 | T | 4,00 |
| Fob Rouen | FCW Superior A2 class 1 majors included Harvest 2026 | Oct. | n.p. | ||
| Fob La Pallice | FAW Superior A2 class 1 majorations included Harvest 2026 | Oct. | n.p. | ||
| Marne departure | BPMF 220 Hagberg Harvest 2026 | Oct.–Dec. | 237,50 | N | 4,00 |
| Departure Eure/Eure-et-Loir | BPMF 76 kg/hl Harvest 2026 | Oct.–Dec. | 239,50 | T | 4,00 |
| Southeast Departure | harvester miller 2026 | Oct.–Dec. | 249,50 | N | 2,50 |
| Corn | Specifications | Deadline | euro/t | Change | |
|---|---|---|---|---|---|
| Bordeaux finish | Harvest 2026 | Oct.–Dec. | inc. | ||
| La Pallice rendering | Harvest 2026 | Oct.–Dec. | Inc. | ||
| Pontivy/Guingamp rendering | Harvest 2026 | Oct.–Dec. | 326,50 | N | 6,00 |
| FOB Bordeaux | Harvest 2026 | Oct.–Dec. | inc. | ||
| Fob Rhin | Harvest 2026 | Oct.–Dec. | 280,00 | T | 10,00 |
| Harvest 2026 | Jan.–Jun. | 281,00 | T | 10,00 | |
| Southeast departure | Harvest 2026 | Oct.–Dec. | inc. |
| Durum wheat | Specifications | Deadline | euro/t | Change | |
|---|---|---|---|---|---|
| Port-la-Nouvelle rendering | semolina standards Harvest 2026 | Oct.–Dec. | 305,00 | N | 10,00 |
| Departure from Eure/Eure-et-Loir | semolina standards Harvest 2026 | Oct.–Dec. | 290,00 | T | 0,00 |
| Southeast departure | Harvest semolina standards 2026 | Oct.–Dec. | 290,00 | N | 5,00 |
| Forage barley | Specifications | Deadline | euro/t | Change | |
|---|---|---|---|---|---|
| Rouen rendering | 62-63 kg/hl Harvest 2026 | Oct.–Dec. | 222,50 | N | -7,00 |
| Pontivy/Guingamp harvest | Harvest 2026 | Oct.–Dec. | 236,50-238,50 | T | 5,00 |
| Fob Moselle | without limit. d'orgettes Harvest 2026 | Oct.–Dec. | 208,50 | T | 4,00 |
| Departure from Eure/Eure-et-Loir | Harvest 2026 | Oct.–Dec. | 214,50 | N | 5,00 |
| Southeast Departure | 65-67 kg/hl Harvest 2026 | Oct.–Dec. | 228,00 | N | 0,00 |
| Brewing barley - Winter 6 rows | Specifications | Deadline | euro/t | Change | |
|---|---|---|---|---|---|
| Fob Creil | Faro 11,5% max Port 500 t Harvest 2026 | Jan.–Jun. | 220,00-221,00 | N | 1,50 |
| Brewing barley - Spring | Specifications | Deadline | euro/t | Change | |
|---|---|---|---|---|---|
| Fob Creil | Planet 11,5% max Port 500 t Harvest 2026 | Jan.–Jun. | 239,00 | A | 1,00 |
| Pois | Specifications | Deadline | euro/t | Change | |
|---|---|---|---|---|---|
| Marne departure | Forage harvest 2026 | Oct.–Dec. | 270,00-275,00 | N | 12,50 |
| Somme/Oise departure | forage Harvest 2026 | October-December | 276,00-281,00 | N | 10,50 |
Milling by-product quotations of 13 October 2026
| Fine soft wheat bran | Specifications | Expiry | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | dispo. | 179,00-181,00 | T | 2,00 | |
| pellets | available. | 199,00-201,00 | T | 5,00 |
| Semi-white remilling | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Île-de-France departure | available. | 199,00-201,00 | T | 5,00 |
| Low-gluten soft wheat flour | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 204,00-206,00 | T | 5,00 |
| Durum wheat porridge | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 204,00-206,00 | T | 5,00 |
Commercial quotations for dairy products of 8 October 2026
| Milk powder | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| NBPL departure in 30 days 5% H BT bulk | available. | 3275,00 | N | 0,00 |
| Whey powder | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| NBPL departure in 30 days, BILA pH 6 bulk | available. | 1650,00 | T | -30,00 |
| Buttermilk | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| without a standard | available. | n.p. | |||
| Dutch standards | available. | n.p. |
Evolution of the dollar / euro on 14 October 2026
| Currency | Value at closing |
|---|---|
| 1 US dollar | 0,8933 euro |
| 1 euro | 1,1195 dollar |
Chicago futures market close on 14 October 2026
| Commodities | Close | Chicago |
|---|---|---|
| Wheat | 673,25 | cents/wood. |
| Corn | 480,75 | cents/wood. |
| Ethanol | 2,161 | $/gallon |
Euronext futures market close on 14 October 2026
| Milling wheat (Euronext) | |
|---|---|
| Deadline | Closing |
| Dec. 2026 | 248,25 |
| March 2027 | 248,00 |
| May 2027 | 246,50 |
| Volume | 98873 |
| Corn (Euronext) | |
|---|---|
| Expiry | Closing |
| Nov. 2026 | 303,00 |
| March 2027 | 280,75 |
| June 2027 | 277,00 |
| Volume | 11247 |
International market quotations for 14 October 2026
| Energy | Due date | Value at close |
|---|---|---|
| Oil (Nymex) | Nov. 2026 | 95,09 $ |
| Sea freight indices | of 14 October | Change |
|---|---|---|
| Baltic Dry Index (BDI) | 2667 | -134,00 |
| Baltic Panamax Index (BPI) | 2409 | -23,00 |
| Baltic Capesize Index (BCI) | 3630 | -364,00 |
| Baltic Supramax Index (BSI) | 1845 | 12,00 |
| Baltic Handysize Index (BHSI) | 1003 | 3,00 |