The essentials:
- Worrying weather conditions for wheat sowing in Russia
- A U.S. corn acreage decrease in 2027/28 in favor of soybeans
- Brazil prioritizes its domestic market for corn
After the surprise caused by the USDA’s release of an increased estimate of US corn yields, wheat and corn prices rebounded on Monday for essentially technical reasons. Risk premiums in the Black Sea are supporting markets, while ample global supplies are limiting any potential for a significant increase.
For all the latest news on agricultural markets, click here
The price of wheat rebounds on the CBOT
CBOT wheat prices gained less than 1 ct$/bushel this Monday, depending on the contract month, after the sharp decline recorded on Friday.
For the December 2026 contract, wheat was up 1,25 cents at 672,25 cts/bushel. The March 2027 contract was also up 0,75 ct$/bushel, at 686 cts/bushel.
Little rain was expected across the U.S. Plains last week, with temperatures above seasonal norms. This allowed winter wheat planting to accelerate. Over the coming week, rain is expected to return to the southern Midwest and central regions, particularly Kansas. Recently planted crops should benefit from wetter conditions, while harvesting could be slowed slightly.
The dollar continued to appreciate against the euro this Monday. The euro was trading at 1,1161 dollar, compared with 1,1202 dollar on Friday. This morning at 7 h 05 (Paris time), it was trading at 1,1174 dollar.
Wheat prices rise very slightly on Euronext
Wheat prices on Euronext were rebounding very slightly, gaining from 1 to 2 €/t depending on the delivery dates.
For the December 2026 contract, the price of wheat rose by 1,25 €/t to 243,25 €/t, while for March 2027, it also gained 1,25 €/t to reach 244,5 €/t.
Tensions in the Black Sea continue to support prices despite abundant global supply. Faced with the collapse in shipments via Black Sea ports, Russia is preparing its first wheat cargo to depart from the Arctic port of Murmansk. About 40 000 tonnes of wheat are to be transported from Stavropol Krai, illustrating the search for new export routes following the sharp decline in flows that usually pass through the country’s southern ports.
Egypt achieved its wheat procurement target from local producers, collecting nearly 5 Mt during the 2026 season. Supported by a harvest of more than 10 Mt, thanks to the expansion of planted areas, this increased production helped strengthen the country's strategic stocks. In this context, Egypt's wheat imports fell to 12,5 Mt, compared with 13,2 Mt in the previous season. The government is thus seeking to reduce its dependence on international markets and limit its exposure to global price volatility.
Russian wheat faces another tense sowing season
The wheat market remains generally well supplied in the short term, despite growing concerns about winter wheat sowing in Russia. The country’s southern regions, its main production areas, are facing a water deficit and high temperatures for the second consecutive year, which could affect the harvest potential of 2027.
Russian farmers are sowing into insufficiently moist soils for the second consecutive year, with a precipitation deficit and above-seasonal temperatures in several southern regions. Key regions such as Krasnodar Krai, Stavropol Krai, and Rostov Oblast are recording limited soil moisture reserves, which could undermine crop establishment and winter hardiness. According to GEOGLAM, Russian winter wheat sowing is significantly behind its usual pace due to a combination of climatic and economic factors.
In its latest report, the USDA lowered its forecast for Russian wheat exports for 2026/27 by 3 Mt, to 40 Mt. This reduction is, however, partially offset by higher export prospects in Canada and Argentina, thereby limiting the immediate impact on the global balance.
In the medium term, two consecutive difficult sowing seasons in Russia could nevertheless increase risks to the global wheat supply if weather conditions do not improve in the coming weeks.
Corn prices are gradually recovering in Chicago
Corn prices on the Chicago CBOT were rebounding this Monday. They were up by 1 to more than 3 cts$/bushel, depending on the contract month.
For the December 2026 contract, the price of corn rose by 3,25 cts$/bushel to 483 cts$/bushel. For the March 2027 contract, it gained 3 cents to reach 497,25 cts$/bushel.
Given the weather conditions observed in the United States last week, corn drying and harvesting accelerated. This week, however, rain is expected to slow harvesting operations.
The energy truce announced yesterday by Donald Trump between Ukraine and Russia does not appear to be in effect. Strikes targeted Ukrainian energy infrastructure this Monday. Oil prices continued to rise following the attack carried out by the Houthis in Saudi Arabia. December Brent futures rose by 1,92% to 106,13 $/barrel, while November WTI futures gained 1,59% to 93,1 $/barrel. This Tuesday morning at 7 h 00 (Paris time), Brent was down 0,64% and WTI 0,59%.
U.S. corn loses ground to soybeans
According to StoneX, the combination of depressed corn prices following the USDA announcement of large global stocks and rising fertilizer costs should prompt U.S. farmers to reduce their corn acreage in favor of soybeans. Rising urea prices are particularly weighing on the crop’s profitability, while corn prices remain under pressure following a record U.S. harvest.
This situation comes as the global market is becoming increasingly dependent on U.S. supplies. Global corn stocks have been substantially replenished thanks to the abundant U.S. harvest, but export availability from other major suppliers remains limited because of logistical disruptions in the Black Sea and growing demand for corn for ethanol production in Brazil.
In this context, a decline in the area planted with corn in the United States could increase the global market’s sensitivity to weather-related risks or any unexpected rise in demand, thereby increasing the potential for price volatility in the coming months.
Brazil prioritizes its domestic corn market over exports
The USDA maintained its forecast for Brazilian corn production at 139 Mt for the 2026/27 season, confirming the country's status as the world's second-largest exporter behind the United States. This harvest is expected to rely on nearly 23,2 million hectares harvested and on the significant contribution of safrinha, second-crop corn sown after soybeans.
Despite this abundant production, exportable supplies could be limited by a sharp increase in domestic consumption. Brazilian corn demand is expected to reach 102 Mt, supported in particular by the rapid development of the bioethanol sector and growing animal feed needs.
As a result of this increased demand, the USDA reduced its forecast for Brazilian corn exports to 43 Mt. Brazil remains a major player in global trade, particularly in Asian markets, but a growing share of its harvest is now being absorbed by its domestic market.
For other exporters, particularly Ukraine, this development could slightly reduce Brazilian competition in the global market. However, Brazil’s influence on international prices will remain significant given the scale of its production and its central role in supplying global importers.
European corn cautiously rebounds on Euronext
Corn prices were slightly higher this Monday. They were up by 2 to 6 €/t, depending on the delivery months.
For the November 2026 delivery, the price of corn rose by 3,75 €/t to 277 €/t. For March 2027, it gained 2,25 €/t to reach 267,5 €/t.
The European corn market remains supported by a historically low European harvest, revised downward by the USDA to 48 Mt from 57 Mt in 2025-2026.
FUNDAMENTALS
Russian wheat exports : 42 Mt versus 43,5 Mt previously estimated (source: IKAR)
Russian wheat production : 88 Mt compared with 88,5 Mt estimated previously (source: IKAR)
French cash markets of 12 October 2026 (July basis for cereals)
| Soft wheat | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Dunkirk rendering | 220/11 miller Harvest 2026 | Oct.–Dec. | 242,00 | N | 1,50 |
| La Pallice rendering | 76/220/11 Harvest 2026 | Oct.–Dec. | 245,50 | N | 1,50 |
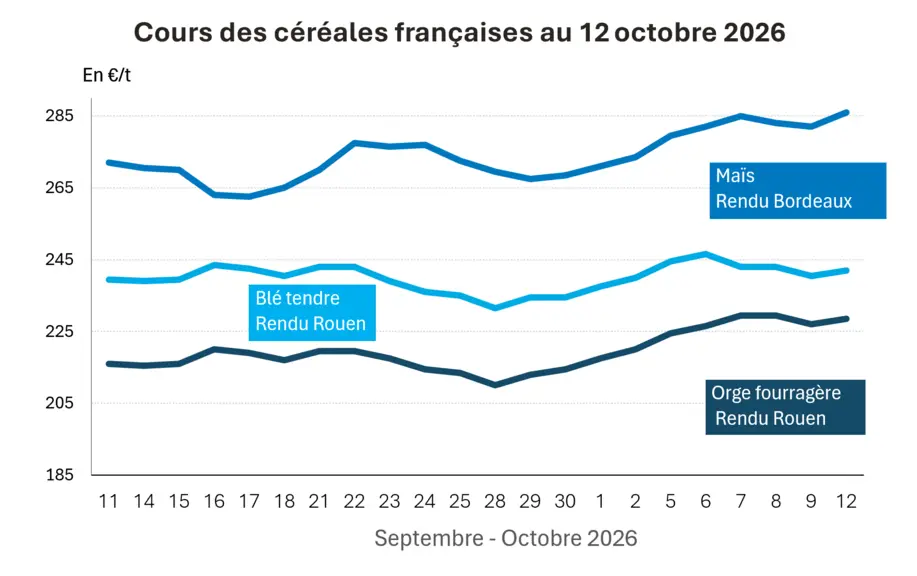
| Rouen Rendering | 76/220/11 Harvest 2026 | Oct.–Dec. | 242,00 | N | 1,50 |
| Pontivy/Guingamp rendering | forage 74 kg/hl base, 72 kg/hl minimum Harvest 2026 | Oct.–Dec. | 244,50 | N | 1,50 |
| Fob Moselle | meunier Harvest 2026 | Oct.–Dec. | 220,50 | N | 1,50 |
| FOB Rouen | Superior FCW A2 class 1 majo. included Harvest 2026 | Oct. | n.p. | ||
| Fob La Pallice | FAW Superior A2 class 1 major. included Harvest 2026 | Oct. | n.p. | ||
| Marne departure | BPMF 220 Hagberg Harvest 2026 | Oct.–Dec. | 232,50 | N | 1,50 |
| Departure from Eure/Eure-et-Loir | BPMF 76 kg/hl Harvest 2026 | Oct.–Dec. | 234,50 | N | 1,50 |
| Southeast departure | meunier Harvest 2026 | Oct.–Dec. | 247,00 | N | 0,00 |
| Corn | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Bordeaux rendering | Harvest 2026 | Oct.–Dec. | 286,00 | N | 4,00 |
| La Pallice rendering | Harvest 2026 | Oct.–Dec. | 288,50 | N | 4,00 |
| Pontivy/Guingamp rendering | Harvest 2026 | Oct.–Dec. | 321,50 | N | 4,00 |
| Fob Bordeaux | Harvest 2026 | Oct.–Dec. | 296,00 | N | 4,00 |
| Fob Rhin | Harvest 2026 | Oct.–Dec. | 271,00 | N | 4,00 |
| Harvest 2026 | Jan.–Jun. | 265,50 | N | 2,00 | |
| Southeast Departure | Harvest 2026 | Oct.–Dec. | 275,00 | N | 0,00 |
| Durum wheat | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Port-la-Nouvelle rendering | semolina standards Harvest 2026 | Oct.–Dec. | 295,00 | N | 0,00 |
| Departure Eure/Eure-et-Loir | seed standards Harvest 2026 | Oct.–Dec. | 290,00 | N | 0,00 |
| Southeast Departure | Seed standards Harvest 2026 | Oct.–Dec. | 285,00 | N | 0,00 |
| Forage barley | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Rendu Rouen | 62-63 kg/hl Harvest 2026 | Oct.-Dec. | 228,50 | N | 1,50 |
| Rendu Pontivy/Guingamp | Harvest 2026 | Oct.–Dec. | 231,50 | N | 1,50 |
| Fob Moselle | without limit. d'orgettes Harvest 2026 | Oct.–Dec. | 203,50 | N | 1,50 |
| Departure Eure/Eure-et-Loir | Harvest 2026 | Oct.–Dec. | 208,50 | N | 1,50 |
| Southeast Departure | 65-67 kg/hl Harvest 2026 | Oct.–Dec. | 228,00 | N | 0,00 |
| Brewing barley - Winter 6 rows | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Fob Creil | Faro 11,5% max Port 500 t Harvest 2026 | Jan.–Jun. | 219,00 | N | 0,00 |
| Brewing barley - Spring | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Fob Creil | Planet 11,5% max Port 500 t Harvest 2026 | Jan.–Jun. | 238,00 | N | 0,00 |
Quotations for milling by-products from 6 October 2026
| Fine soft wheat | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 177,00-179,00 | T | 0,00 | |
| pellets | available. | 194,00-196,00 | T | 0,00 |
| Semi-white regrinding | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 194,00-196,00 | T | 0,00 |
| Low-gluten soft wheat flour | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 199,00-201,00 | T | 0,00 |
| Durum wheat porridge | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 199,00-201,00 | T | 0,00 |
Dairy product market quotations for 8 October 2026
Stay up to date in real time!
Follow topics, legislative projects, companies, and personalities to be notified as soon as we publish an article.
futures market
Follow-up
Follow
markets
Follow-up
Follow
| Milk powder | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| NBPL departure in 30 days 5% H BT bulk | available. | 3275,00 | N | 0,00 |
| Whey powder | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| NBPL departure in 30 days, BILA pH 6 bulk | available. | 1650,00 | T | -30,00 |
| Buttermilk | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| without a standard | available. | n.p. | |||
| Dutch standards | available | n.p. |
Dollar / euro evolution on 12 October 2026
| Devise | Closing value |
|---|---|
| 1 US dollars | 0,8944 euros |
| 1 euros | 1,1181 dollars |
Chicago futures market close on 12 October 2026
| Commodities | Closing | Chicago |
|---|---|---|
| Wheat | 672,25 | Cents/wood. |
| Corn | 483,00 | cents/wood. |
| Ethanol | 2,161 | $/gallon |
Euronext futures market close on 12 October 2026
| Milling wheat (Euronext) | |
|---|---|
| Expiry | Closing |
| Dec. 2026 | 243,25 |
| Mars 2027 | 244,50 |
| Mai 2027 | 244,00 |
| Volume | 60766 |
| Corn (Euronext) | |
|---|---|
| Due date | Closing |
| Nov. 2026 | 277,00 |
| Mars 2027 | 267,50 |
| June 2027 | 263,50 |
| Volume | 4532 |
International market quotations for 12 October 2026
| Energy | Deadline | Closing value |
|---|---|---|
| Petroleum (Nymex) | Nov. 2026 | 93,74 $ |
| Ocean freight indices | from 9 October | Change |
|---|---|---|
| Baltic Dry Index (BDI) | 2917 | -56,00 |
| Baltic Panamax Index (BPI) | 2424 | 14,00 |
| Baltic Capesize Index (BCI) | 4340 | -172,00 |
| Baltic Supramax Index (BSI) | 1814 | 6,00 |
| Baltic Handysize Index (BHSI) | 996 | -4,00 |