France
French Pork Market
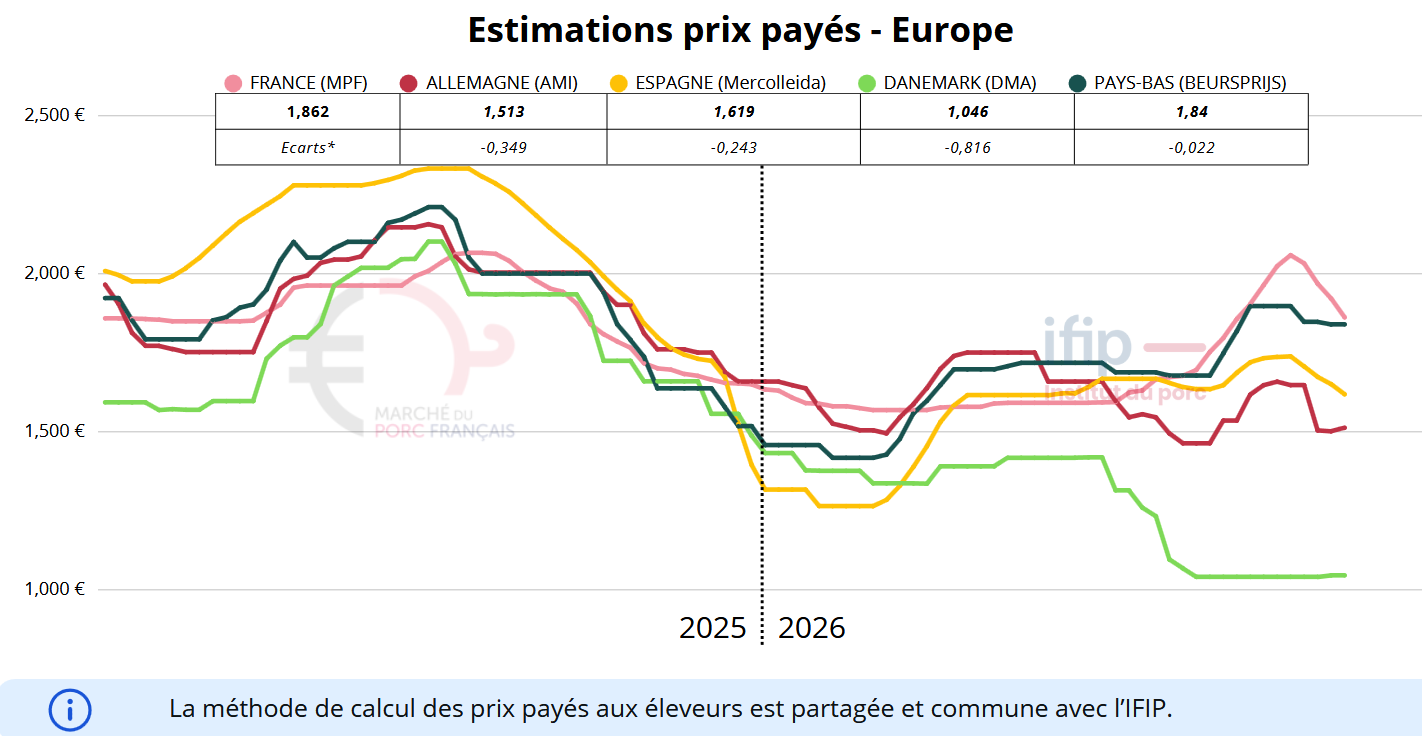
For the third consecutive week, the French Pork Market recorded a cumulative maximum decrease of 6 cents over the two sales sessions. For the time being, all buyers are maintaining this position, with very close bids reflecting a widespread desire to adjust the price downward. Faced with increasingly numerous offers, sellers have little choice but to accept these declines.
Uniporc
While slaughter volumes fell last week, weights continue to rise and have now reached the levels of 2025. This means that, despite lower pig availability than last year, slaughterhouse needs are more than adequately covered by a growing seasonal supply. This new market balance is putting downward pressure on pork prices in France.
European Union
The German price remains stable at 1,45 €/kg, but supply remains too abundant in several regions and disruptions linked to the public holiday persist. Slaughter numbers fall to 692 747 pigs, while weights rise to 98,2 kg. Promotions provide further support to demand and allow all cuts to be sold, especially shoulders, hocks and spare ribs. Buyers nevertheless remain cautious. Stability prevails this week, but downward pressure in the medium term cannot be ruled out.
The Spanish price falls again. Weights remain about 3,7 kg below their level in 2025, and some areas even report tight availability. By contrast, meat prices are falling faster than pig prices, keeping slaughterhouse margins under severe pressure. The national public holiday on 12 October will eliminate one slaughter day.
In Italy, the price is falling even though the supply of pigs remains insufficient to fully meet demand. However, resistance from slaughterhouses is intensifying, as the deterioration of the European meat market is gradually reducing their room for maneuver. The market is therefore supported by the shortage of supply, but its potential for growth has quickly reversed.
United States and China
The U.S. market continues its seasonal decline, with a drop of 2,4 % in the reference price and 1,1 % in the value of cuts. Slaughter numbers rise to 2,56 million pigs, slightly above 2025. Cold storage stocks exceed last year’s level by 12 %. This accumulation, combined with less dynamic external demand, keeps pressure on prices.
The Chinese market remains under pressure despite national holidays, as festive demand is insufficient to absorb abundant supply. Livestock shipments continue to weigh on prices. Meanwhile, soybean stocks reach historically high levels, while a reduction in the breeding herd is expected. These developments could contribute to a gradual rebalancing of the market.