Key points:
- The market has factored in this week’s attacks on merchant ships in the Black Sea and on Russian port terminals.
- Dry conditions in parts of Ukraine and Russia delay the sowing of winter wheat.
- TheUSDA lowered the good to excellent growing conditions by 3 points to 54% for the corn to United States, which worried the markets.
Attacks in the Black Sea continue to drive demand for European wheat
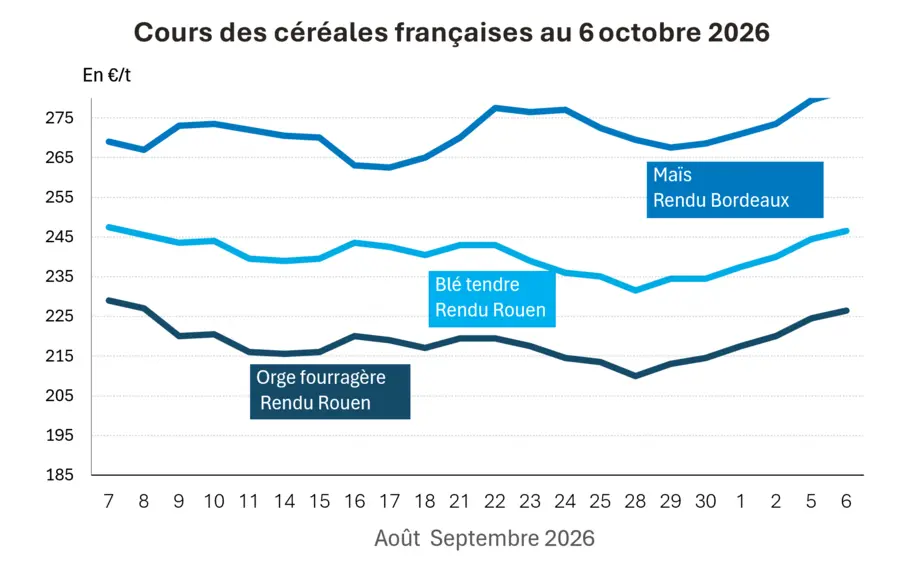
The prices of the wheat gained 1,75 €/t on Euronext’s December and March contracts between 5 and 6 October, closing at 247,50 €/t for December. Corn contracts saw a sharper rise, gaining 2,25 €/t for November, 3,50 €/t for March, and 3,25 €/t for June and August. They stood at 277 €/t on Tuesday evening.
In Europe, the tense situation in the Black Sea was the main factor driving wheat prices higher, combined with sustained international demand. Russian strikes on merchant ships off the coast of Bulgariand from RomaniaEarly in the week, concerns also emerged about the export prospects of these two countries.
In addition, Ukrainian attacks are slowing operations at some terminals in the port of Novorossiysk. This is reflected in the flows departing from Russia : according to Graintrade, cumulative wheat exports since the start of the season were down 62,8% compared with last year; a figure rising to 74% for September alone. In Ukraine, logistics costs to Polish and Romanian ports are rising, while the availability of grain wagons is limited. According to Graintrade, this has led traders to lower their purchase prices in Ukraine.
To find out all the latest news about agricultural markets, click here
On the importers’ side, they are being cautious and continue to wait. The’Egypt would thus have reduced its wheat purchases by 76,6% in September compared with 2025, Graintrade reports. Demand nevertheless remains, and buyers are turning to the wheat dWestern Europe, supporting prices on Euronext and French physical market quotations.
Also worth noting is the water deficit affecting a third of Ukraine’s winter wheat-growing areas and part of Russia. Operators fear that the area under cultivation in the country of the Tsars will shrink due to drought and a sharp decline in exports.
European corn prices are rising in step with their U.S. counterpart
Quotations for the corn gained 2,25 €/t on the November delivery ofEuronext, closing at 277 €/t. The increase was more pronounced for the March, June and August contracts (+ 3,5 €/t for March and +3,25 €/t for June and August). Technical factors, along with the rise in US yellow soybean prices, fuelled the price increase. European imports also remain sharply higher at the start of the marketing year compared with the previous one, according to thea European Commission.
Surprise decline in the share of U.S. corn crops rated good to excellent
TheUSDA lowered the yellow seed’s good-to-excellent crop conditions by 3 points yesterday, to United States. These now represent 54% of production. This unexpected change caught markets and the prices of corn to Chicago have gained ground across all 2026 harvest maturities, rising in particular by 10,75 cents on December. According to Matt Zeller of StoneX, cited by Lachstock Consulting, the note of corn U.S. is now only one point above what it was at 2023, the worst crop rating recorded since 2012. As for the harvest, rains in Iowa have delayed it somewhat. It is 4 points below the 2025 harvest. The dry week ahead should provide a harvest window. Consultant Michael Cordonnier, for his part, left his yield forecast unchanged at 177,0 bushels per acre.
Rainfall complicates corn planting in southern Brazil
In Brazil, corn planting for the first crop is slightly behind last year’s pace, according to AgRural. Conversely, in Argentine, hot and dry conditions do not bode well for corn planting.
Rise in wheat prices in the United States
The courses of the wheat gained ground on futures markets (Chicago, Kansas City, and Minneapolis) across all maturities. In particular, they gained 12 cents per tonne for the December contract on the CBOT.The situation in the Black Sea has also affected prices. Winter wheat sowing and emergence are slightly behind the five-year average, reports theUSDA. U.S. wheat exports also increased month over month, still according to theUSDA.
In Australia, the barley harvest is expected to begin next week in the state of New South Wales, and the water deficit in Victoria could lower yield potential, warns Lachstock consulting.
Fundamentals:
United States, corn, crop conditions: 54% good to excellent as of October 4 versus 57% last week (source: USDA)
United States, corn, harvest: completed at 23% as of 4 October, compared with 18% the previous week and 27% according to the five-year average (source: USDA)
United States, winter wheat, sowing: completed at 36% as of 4 October, compared with 27% last week and 46% according to the five-year average (source: USDA)
United States, winter wheat, emergence: complete at 16% as of 4 October, compared with 8% last week and 20% according to the five-year average (source: USDA)
United States, corn, yield: 177,0 bushels per acre, unchanged (source: Soybean & Corn)
International trade:
Ukraine, wheat, exports: 118 000 t as of 5 October, compared with 383 000 t last year, i.e. 2,89 Mt since the start of the campaign, compared with 5,12 Mt in 2025 (source: Graintrade)
Stay up to date in real time!
Follow topics, legislative projects, companies, and public figures to be notified as soon as we publish an article.
Russia, wheat, exports: 1,7 Mt in September 2026 versus 6,5 Mt in 2025 (i.e., – 74 %) and 4,5 Mt over 2026-2027 as of October 1er versus 12,1 Mt in 2025-2026, i.e., -62,8 % (source: Graintrade)
Egypt, wheat, imports: 362 500 t in September 2026 versus 1,548 Mt in 2025 (source: Graintrade)
United States, corn, exports: 7,422 Mt for the month of August, up 25,7% compared with July (source: USDA)
French physical markets as of 6 October 2026 (July basis for cereals)
| Common wheat | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Dunkirk Rendering | 220/11 Meunier Harvest 2026 | Oct.–Dec. | 246,50 | N | 2,00 |
| La Pallice rendering | 76/220/11 Harvest 2026 | Oct.–Dec. | 249,50 | N | 2,00 |
| Rouen rendering | 76/220/11 Harvest 2026 | Oct.–Dec. | 246,50 | N | 2,00 |
| Pontivy/Guingamp rendering | forage 74 kg/hl base, 72 kg/hl mini Harvest 2026 | Oct.–Dec. | 248,50 | N | 2,00 |
| Moselle fob | meunier harvest 2026 | Oct.–Dec. | 227,50 | N | 2,00 |
| Fob Rouen | FCW Superior A2 class 1 incl. VAT Harvest 2026 | Oct. | 254,79 | N | |
| Fob La Pallice | FAW Upper A2 class 1 majors included Harvest 2026 | Oct. | 258,09 | N | |
| Departure Marne | BPMF 220 Hagberg Harvest 2026 | Oct.–Dec. | 237,50 | N | 2,00 |
| Departure Eure/Eure-et-Loir | BPMF 76 kg/hl Harvest 2026 | Oct.–Dec. | 239,50 | N | 2,00 |
| Southeast Departure | meunier Harvest 2026 | Oct.–Dec. | 236,50 | N | 0,00 |
| Corn | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Bordeaux rendering | Harvest 2026 | Oct.–Dec. | 282,00 | N | 2,50 |
| La Pallice rendering | Harvest 2026 | Oct.–Dec. | 286,00 | N | 2,50 |
| Pontivy/Guingamp rendering | Harvest 2026 | Oct.–Dec. | 322,00 | N | 2,50 |
| Bordeaux fob | Harvest 2026 | Oct.–Dec. | 294,00 | N | 2,50 |
| Fob Rhin | Harvest 2026 | Oct. | n.p. | ||
| Harvest 2026 | Jan.–Jun. | 274,00 | N | 3,50 | |
| Southeast departure | Harvest 2026 | Oct.–Dec. | inc. |
| Durum wheat | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Rendering Port-la-Nouvelle | semolina standards Harvest 2026 | Oct.–Dec. | 295,00 | N | 0,00 |
| Departure Eure/Eure-et-Loir | semolina standards Harvest 2026 | Oct.–Dec. | 285,00 | N | 0,00 |
| Southeast departure | semolina standards Harvest 2026 | Oct.–Dec. | 285,00 | N | 0,00 |
| Forage barley | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Rendu Rouen | 62-63 kg/hl Harvest 2026 | Oct.–Dec. | 226,50 | N | 2,00 |
| Pontivy/Guingamp rendering | Harvest 2026 | Oct.–Dec. | 236,50 | N | 2,00 |
| Moselle key fob | without limit. d'orgettes Harvest 2026 | Oct.–Dec. | 208,50 | N | 2,00 |
| Departure: Eure/Eure-et-Loir | Harvest 2026 | Oct.–Dec. | 213,50 | N | 2,00 |
| Southeast Departure | 65-67 kg/hl Harvest 2026 | Oct.-Dec. | 225,00 | N | 0,00 |
| Brewing barley - Winter 6 rows | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Fob Creil | Lighthouse 11,5% max Port 500 t Harvest 2026 | Jan.–Jun. | 213,00-217,00 | N | 0,00 |
| Brewing barley - Spring | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Fob Creil | Planet 11,5% max Port 500 t Harvest 2026 | Jan–Jun | 230,00 | N | 0,00 |
Quotations for milling by-products as of 6 October 2026
| Its fine soft wheat | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 177,00-179,00 | T | 0,00 | |
| pellets | available. | 194,00-196,00 | T | 0,00 |
| Semi-white regrinding | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 194,00-196,00 | T | 0,00 |
| Low-gluten soft wheat flour | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 199,00-201,00 | T | 0,00 |
| Durum wheat groats | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| Departure from Île-de-France | available. | 199,00-201,00 | T | 0,00 |
Dairy product market quotations for 1 October 2026
| Milk powder | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| NBPL departure in 30 days 5% H BT bulk | available. | 3275,00 | N | 0,00 |
| Whey powder | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| NBPL departure in 30 days, BILA pH 6 bulk | avail. | 1680,00 | N | 0,00 |
| Buttermilk | Specifications | Deadline | euro/t | Variation | |
|---|---|---|---|---|---|
| without a standard | avail. | n.p. | |||
| Dutch standards | available. | n.p. |
Dollar / euro evolution as of 6 October 2026
| Device | Value at closing |
|---|---|
| 1 US dollars | 0,8874 euros |
| 1 euros | 1,1269 dollars |
Chicago futures market close on 6 October 2026
| Commodities | Closing | Chicago |
|---|---|---|
| Wheat | 704,25 | cents/wood. |
| Corn | 508,00 | cents/wood. |
| Ethanol | 2,161 | $/gallon |
Euronext futures market close on 6 October 2026
| Milling wheat (Euronext) | |
|---|---|
| Expiry | Closing |
| Dec. 2026 | 247,50 |
| March 2027 | 249,25 |
| May 2027 | 248,50 |
| Volume | 92165 |
| Corn (Euronext) | |
|---|---|
| Deadline | Closing |
| Nov. 2026 | 277,00 |
| Mars 2027 | 272,75 |
| June 2027 | 269,50 |
| Volume | 5492 |
International market quotations for 6 October 2026
| Energy | Deadline | Closing value |
|---|---|---|
| Oil (Nymex) | Nov. 2026 | 89,44 $ |
| Ocean freight indices | from 6 October | Variation |
|---|---|---|
| Baltic Dry Index (BDI) | 3002 | -68,00 |
| Baltic Panamax Index (BPI) | 2366 | 2,00 |
| Baltic Capesize Index (BCI) | 4638 | -195,00 |
| Baltic Supramax Index (BSI) | 1795 | 5,00 |
| Baltic Handysize Index (BHSI) | 1005 | 1,00 |