France
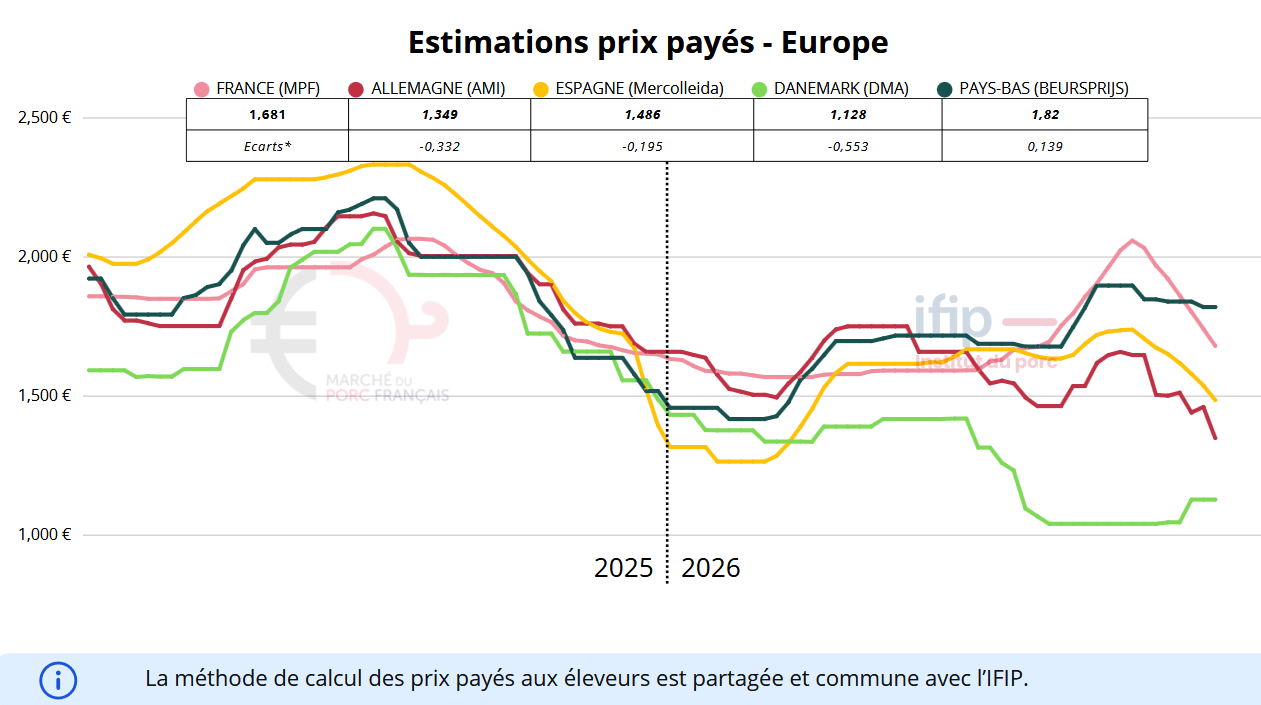
French pork market: The downward trend at the French Pork Market remains just as pronounced, with a further cumulative decline of 6 cents over the two sessions last week. Auction bids remain firm and are concentrated around the maximum declines allowed under the agreement, namely 1 and 5 cents respectively. With pork supplies increasing, sellers are unable to offer any real resistance to this downward movement.
Uniporc: Slaughter numbers increased for the second consecutive week, reaching nearly 350 000 pigs. However, they remain around 10 000 pigs below the level in 2025. Meanwhile, carcass weights continued their seasonal rise, with a difference of 410 grams compared with 2025.
European Union
The German reference price falls by 8 cents to 1,32 €/kg, following persistent demands from slaughterhouses for several weeks. Slaughter numbers remain relatively stable at 736 244 pigs, and weights hold at 98,6 kg. Supply is increasing while slaughterhouse demand remains limited. The meat trade remains difficult, both on the domestic market and for export. This new decrease could once again intensify pressure on other European markets.
The Spanish market remains under pressure, with pig supply increasing and weights rising rapidly. The average weight reaches 89,56 kg, up 1,2 kg in one week, but remains around 2,5 kg below that of 2025. Slaughterhouses continue to take the available animals, but difficulties in marketing the meat are weighing on prices.
The Belgian market maintains a particular situation, with relatively limited availability of pigs and slaughterhouses still looking for supplies. This competition between slaughterhouses is helping to support quotations, despite the deterioration of the European market. The meat trade remains difficult, however, and low prices for cuts are penalizing slaughter companies. Germany’s latest reduction of 8 cents is adding to the pressure, but the needs of Belgian slaughterhouses are limiting its impact on domestic quotations.
United States and China
In the United States, slaughter is up 1 % year on year, in a meat market that remains depressed. The value of cuts is down 3,2 %, notably due to lower prices for ribs and ham. Pig prices fell 4,1 % over the week and now stand 25 % below their level in 2025. Slaughterhouse margins remain particularly low, which could intensify pressure on the prices paid to farmers as seasonal availability increases.
In China, live pig prices continue to fall despite a slight improvement in meat purchases. Supplies remain ample, with large farms maintaining high volumes while independent producers accelerate their sales. Demand is showing some signs of recovery, but remains insufficient to absorb supply. In this context, prospects for a price recovery remain limited in the short term.