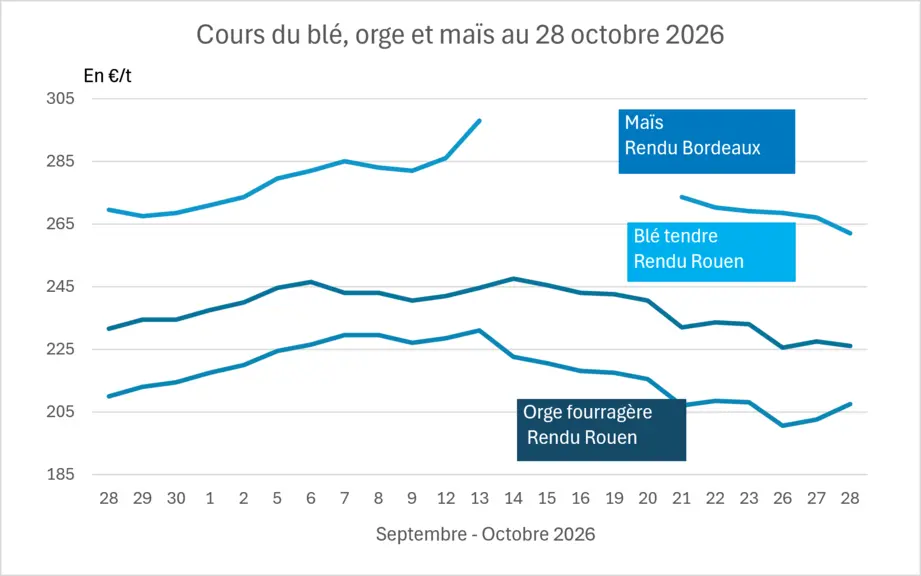
Key points on the grain market
-
Prospects for a resumption of shipments via the Black Sea following the partial reopening of the Sea of Azov.
-
Potential wheat purchases by the World Food Programme and increasingly clear Brazilian demand.
-
Significant barley availability in Australia.
-
Global demand for grain remains strong, but ample supplies are taking precedence in the markets.
The essentials for the euro/dollar and oil
-
At the end of its Federal Open Market Committee (FOMC) meeting, the United States Federal Reserve (FED) left its key interest rates unchanged, but noted that inflation in the country “continues to cause concern” and is accelerating this month, which could signal a change in interest rates at the next meeting on 9 and 10 December. The €/$ exchange rate closed on Wednesday at 1,1152, compared with 1,1130 on Tuesday, and was trading at around 1,1139 this morning at around 7h45 French time.
-
WTI crude oil closed higher on Wednesday at 102,08 $ compared with 100,12 $ on Tuesday, while the European benchmark Brent closed at 114,34 dollars compared with 114,20 $ the previous day. Following the parliamentary elections in Israel, the United States is contemplating a swift, targeted military operation against Iran. At the same time, Iran says it is negotiating the passage of ships through the Strait of Hormuz.
To find out everything about agricultural market news, click here
Grain prices continued to fall on Wednesday, amid hopes of a resumption of grain traffic in the Black Sea, while Ukrainian stocks remain high. Only corn traded on the CBOT rebounded slightly, supported by excessively wet weather conditions in some regions of the United States.
CBOT wheat prices fall back below 600 cents/bushel
Wheat prices lost between 1 and more than 11 cents/bushel across the contract months this Wednesday. Declines were particularly steep in nearby contracts, amid hopes of a reopening of Black Sea exports, despite continued strong international demand.
For the December 2026 contract, the most active, wheat was down 11,25 cents, at 599 cents/bushel. The March and May 2027 contracts were down respectively 9,75 and 9 cents/bushel, settling at 613,25 and 620 cents/bushel.
World Food Programme: up to 1 million tonnes of Ukrainian grain potentially purchased
As of October 1st, grain and oilseed stocks in Ukraine had reached 20,7 million tonnes, or 6 million tonnes more than a year earlier.
In 23 October, 20 718 freight wagons were waiting at Ukraine's western border crossings, with an average crossing time of 19 days.
However, the World Food Programme (WFP) declares itself ready to acquire up to 1 million tonnes of Ukrainian grain for its humanitarian programs, subject to the availability of the necessary funding and logistics.
Brazil could reach a record level of wheat imports
Brazil could import up to 10 million tonnes of wheat in 2027, an unprecedented volume in more than thirty years, due to a sharp drop in its production and weather-related quality problems.
The national harvest would cover only 36% of the country's needs.
While Argentina remains Brazil’s main supplier and could benefit from an abundant harvest, concerns also persist about the quality of Argentine wheat after several episodes of excessive rain and frost.
Australia targets record barley exports thanks to Chinese demand
Australia is expected to harvest 17,7 million tonnes of barley in 2026/27 and could export a record volume of 13 million tonnes, supported by strong Chinese demand.
At the same time, wheat production is expected to reach 32 Mt, compared with 36 Mt the previous campaign.
This abundant Australian barley supply increases competition among exporters and is a somewhat bearish factor for global barley prices, even as Chinese demand absorbs a significant share of available supplies.
Wheat trades between 226 and 227 €/t on Euronext
Following the US market, wheat prices on Euronext were down by between 0,5 and more than 2 €/t on near-term maturities, while they remained broadly stable on longer-term maturities.
For the December 2026 maturity, the wheat price fell by 1,50 €/t, at 227 €/t. The March and May 2027 deadlines were both around 226 €/t, decreasing by 2,25 €/t and 1,75 €/t.
Financial operators reduced their net long position in Euronext wheat by approximately 42 100 lots, bringing it back to 111 200 lots.
It should also be noted that the Tunisia purchased 100 000 tonnes of wheat at C&F prices ranging between 296,91 $/t and 304,89 $/t. For its part, Jordan launched a new international tender for up to 120 000 tonnes of milling wheat, with a bid submission deadline set for 3 November 2026.
Russia reopens the Sea of Azov: global wheat under pressure
Russia has authorized the departure of grain ships from the ports of, for the first time since July 2026Temryuk and Kavkaz, located in the Sea of Azov.
This decision allows a partial resumption of grain shipments through the Kerch Strait to the Black Sea.
The announcement immediately weighed on markets. Chicago wheat futures fell as much as 2,8 %, reaching their lowest level since early July.
However, logistical and security risks remain high in the absence of a ceasefire, limiting the actual impact on trade flows for now.
Exports to Turkey are said to have fallen nearly eightfold and those to Egypt more than sevenfold. The number of destinations for Russian wheat is also said to have risen from 29 to 15 countries in one year. Georgia appears to be a growing outlet for Russian wheat, but this market nevertheless remains too limited to offset the decline in sales to Russia’s main customers.
Corn prices rebound slightly on the CBOT
Corn prices in Chicago edged up this Wednesday. The more distant contracts declined, while nearby contracts were unchanged or rose by 1 to 3 cents/bushel.
For the December 2026 contract, still the most active, corn stood at 452,75 cents/bushel, up by 3 cents, after losing 6,25 cents the day before.
The March 2027 deadline stood at 462,75 cents/bushel.
European corn falls again on Euronext
Corn prices on Euronext were falling by between 1 and close to 5 €/t on most maturities, with the exception of the November maturity, which was very thinly traded and rose by 4,75 €/t to 288 €/t.
For the March 2027 contract, currently the main maturity being traded, corn was down by 3,75 €/t to 259,50 €/t. The May 2027 deadline, for its part, was giving up 3,25 €/t to 257,25 €/t.
According to the latest trader positions report published by Euronext on 23 October, financial operators reduced their net long position on corn by approximately 400 lots, to return to 11 000 lots.
French physical markets of 28 October 2026 (July basis for cereals)
|
Soft wheat |
Specifications |
Deadline |
euro/t |
|
Change |
|---|---|---|---|---|---|
|
Dunkirk rendering |
220/11 miller Harvest 2026 |
Oct.–Dec. |
226,50 |
T |
-0,50 |
|
La Pallice harbor |
76/220/11 Harvest 2026 |
Oct.–Dec. |
230,50 |
T |
-0,50 |
|
Rouen rendering |
76/220/11 Harvest 2026 |
Oct.–Dec. |
226,00 |
T |
-1,50 |
|
Pontivy/Guingamp yield |
forage 74 kg/hl base, 72 kg/hl mini Harvest 2026 |
Oct.–Dec. |
233,00 |
T |
-1,50 |
|
Fob Moselle |
meunier Harvest 2026 |
Oct.–Dec. |
207,50 |
T |
-1,00 |
|
Fob Rouen |
FCW Superior A2 class 1 major. included Harvest 2026 |
Oct. |
n.p. |
|
|
|
Fob La Pallice |
FAW Superior A2 class 1 major inclusions Harvest 2026 |
Oct. |
n.p. |
|
|
|
Marne departure |
BPMF 220 Hagberg Harvest 2026 |
Oct.–Dec. |
inc. |
|
|
|
|
BPMF 220 Hagberg Harvest 2026 |
Jan.–Mar. |
212,50 |
T |
|
|
Starting point: Eure/Eure-et-Loir |
BPMF 76 kg/hl Harvest 2026 |
Oct.–Dec. |
218,50 |
T |
-1,00 |
|
Southeast departure |
harvester miller 2026 |
Oct.–Dec. |
225,00 |
T |
-10,00 |
|
Corn |
Specifications |
Deadline |
euro/t |
|
Change |
|---|---|---|---|---|---|
|
Bordeaux vintage |
Harvest 2026 |
Jan.–Mar. |
262,00 |
N |
-4,50 |
|
La Pallice Harvest |
Harvest 2026 |
Jan.–Mar. |
262,00 |
T |
-7,00 |
|
Pontivy/Guingamp rendering |
Harvest 2026 |
Oct.–Dec. |
332,00 |
T |
23,00 |
|
Fob Bordeaux |
Harvest 2026 |
Oct.–Dec. |
inc. |
|
|
|
Fob Rhin |
Harvest 2026 |
Oct.–Dec. |
266,00 |
T |
0,50 |
|
|
Harvest 2026 |
Jan.–June |
268,00 |
T |
0,50 |
|
Southeast departure |
Harvest 2026 |
Oct.–Dec. |
incl. |
|
|
|
|
Harvest 2026 |
Jan.–June |
280,00 |
T |
|
|
Durum wheat |
Specifications |
Deadline |
euro/t |
|
Variation |
|---|---|---|---|---|---|
|
Rendering Port-la-Nouvelle |
semolina standards Harvest 2026 |
Oct.–Dec. |
310,00 |
V |
2,50 |
|
Departure Eure/Eure-et-Loir |
semolina standards Harvest 2026 |
Oct.–Dec. |
292,00 |
N |
-3,00 |
|
Southeast Departure |
semolina standards Harvest 2026 |
Oct.–Dec. |
295,00 |
N |
5,00 |
|
Forage barley |
Specifications |
Deadline |
euro/t |
|
Variation |
|---|---|---|---|---|---|
|
Rendu Rouen |
62-63 kg/hl Harvest 2026 |
Oct.–Dec. |
207,50 |
T |
5,00 |
|
Pontivy/Guingamp rendering |
Harvest 2026 |
Oct.–Dec. |
219,50 |
T |
0,00 |
|
Fob Moselle |
unlimited. d'orgettes Harvest 2026 |
Oct.–Dec. |
206,50 |
T |
20,00 |
|
Departure Eure/Eure-et-Loir |
Harvest 2026 |
Oct.–Dec. |
198,50 |
T |
2,00 |
|
Southeast departure |
65-67 kg/hl Harvest 2026 |
Oct.–Dec. |
215,00 |
T |
-13,50 |
|
Brewing barley - Winter 6 rows |
Specifications |
Deadline |
euro/t |
|
Variation |
|---|---|---|---|---|---|
|
Fob Creil |
Faro 11,5% max Port 500 t Récolte 2026 |
Jan.–Jun. |
214,00-215,00 |
T |
-6,50 |
|
Brewing barley - Spring |
Specifications |
Deadline |
euro/t |
|
Variation |
|---|---|---|---|---|---|
|
Fob Creil |
Planet 11,5% max Port 500 t Harvest 2026 |
Jan.-June |
236,00-238,00 |
N |
-6,00 |
Milling by-product quotations for 27 October 2026
|
Fine soft wheat bran |
Specifications |
Expiry |
euro/t |
|
Variation |
|---|---|---|---|---|---|
|
Departure from Île-de-France |
|
available. |
179,00-181,00 |
T |
-5,00 |
|
|
pellets |
disposal. |
194,00-196,00 |
T |
-5,00 |
|
Semi-white remilling |
Specifications |
Deadline |
euro/t |
|
Variation |
|---|---|---|---|---|---|
|
Departure from Île-de-France |
|
available. |
194,00-196,00 |
T |
-5,00 |
|
Low-gluten soft wheat flour |
Specifications |
Deadline |
euro/t |
|
Variation |
|---|---|---|---|---|---|
|
Departure from Île-de-France |
|
available. |
194,00-196,00 |
T |
-5,00 |
|
Durum wheat porridge |
Specifications |
Deadline |
euro/t |
|
Variation |
|---|---|---|---|---|---|
|
Departure from Île-de-France |
|
available. |
199,00-201,00 |
T |
-5,00 |
Dairy product market quotations for 22 October 2026
|
Milk powder |
Specifications |
Deadline |
euro/t |
|
Variation |
|---|---|---|---|---|---|
|
|
NBPL departure in 30 days 5% H BT bulk |
available. |
3600,00 |
T |
325,00 |
|
Whey powder |
Specifications |
Deadline |
euro/t |
|
Variation |
|---|---|---|---|---|---|
|
|
NBPL departure in 30 days, BILA pH 6 bulk |
available. |
1650,00 |
T |
0,00 |
|
Buttermilk |
Specifications |
Deadline |
euro/t |
|
Variation |
|---|---|---|---|---|---|
|
|
without a standard |
available. |
n.p. |
|
|
|
|
Dutch standards |
available. |
n.p. |
|
|
Dollar / euro exchange rate as of 28 October 2026
|
Currency |
Value at closing |
|---|---|
|
1 US dollar |
0,8982 euro |
|
1 euro |
1,1133 dollars |
Chicago futures market close of 28 October 2026
|
Commodities |
Close |
Chicago |
|---|---|---|
|
Wheat |
599,00 |
cents/wood. |
|
Corn |
451,75 |
cents/wood. |
|
Ethanol |
2,161 |
$/gallon |
Euronext futures market close on 28 October 2026
|
Milling wheat (Euronext) |
|
|---|---|
|
Deadline |
Closing |
|
Dec. 2026 |
227,00 |
|
March 2027 |
225,75 |
|
May 2027 |
226,25 |
|
Volume |
167368 |
|
Corn (Euronext) |
|
|---|---|
|
Expiry |
Closing |
|
Nov. 2026 |
288,00 |
|
March 2027 |
259,50 |
|
June 2027 |
257,25 |
|
Volume |
4731 |
International market quotations for 28 October 2026
|
Energy |
Expiry |
Closing value |
|---|---|---|
|
Oil (Nymex) |
Dec. 2026 |
102,78 $ |
|
Maritime freight indices |
of 28 October |
Change |
|---|---|---|
|
Baltic Dry Index (BDI) |
2652 |
49,00 |
|
Baltic Panamax Index (BPI) |
1965 |
-56,00 |
|
Baltic Capesize Index (BCI) |
3886 |
184,00 |
|
Baltic Supramax Index (BSI) |
1878 |
-5,00 |
|
Baltic Handysize Index (BHSI) |
1017 |
-3,00 |