
Prices keep falling! Pig prices have dropped by more than 15%; where is the “floor” from here?
Down, down—the “Second Brother” just keeps falling! The live pig market has fallen into a “cold winter.” Although seasonal demand is nominally in its peak season, consumption this month has cooled noticeably. After the Mid-Autumn Festival and National Day holidays, seasonal demand came under temporary pressure, and the pace of movement in the market slowed. Demand from urban catering and group meals cooled, while in the domestic market, although falling temperatures were favorable for meat demand, egg prices fell sharply, poultry prices remained weak, and supplies of beef and mutton were ample. Substitute consumption was widespread, further limiting sales of fresh pork carcasses!
With consumption remaining sluggish, downstream market vendors have mainly reduced volumes to stabilize prices, while slaughterhouses have mostly maintained a production-to-order model. So far, the operating rate at sampled slaughterhouses is around 30.41%, and marginal demand is low. Raising the price of fresh pork carcasses is also difficult. At present, the average price of domestic Grade Three fresh pork carcasses is 13.09 yuan/kg. Compared with the average price of standard pigs, the spread is only 3.69 yuan/kg, and slaughterhouse losses are deepening! Steel Union Data monitoring shows that slaughterhouses lost 13.4 yuan per head this week, an increase of 5.6 yuan per head compared with the previous week. Major slaughterhouses are strongly inclined to use the opportunity to push prices down.
In particular, regarding frozen pork inventories, frozen pork stocks this week stood at 31.77%, down 0.1 percentage points from the previous week. Increased shipments of frozen pork further suppressed the market share of fresh pork sales, worsening the weak demand situation!
Meanwhile, on the domestic supply side, it is well known that the number of breeding sows affects market hog shipments 10 months later. Based on the earlier breeding sow inventory of 3961 ten thousand head, an increase of 4 ten thousand head month on month, and generally improved sow production efficiency of 25-30 head, the substantial efficiency gains have strengthened this month's market hog supply capacity! In addition, some pig companies fell short of their shipment plans last month, and some production capacity was consequently shifted to later shipments, further increasing the actual shipment plans for 10 month! According to Zhuochuang data monitoring, shipments by large-scale pig companies increased 2.45% month on month this month.
In addition, recently, as the weather has turned cooler in northern and southern regions, weight gain in fattening pigs has accelerated. As of this week, the average shipment weight of live pigs had increased to 124.49 kilograms, up 0.16 kilograms from last week. This week, the average slaughter weight per head at slaughterhouses increased by 0.15 kilograms to 93.93 kilograms, further strengthening pork supply capacity!
As for bargain hunting, the supply outlook is ample, seasonal peak demand has been lackluster, long-term fattening of live pigs has been loss-making, and major secondary-fattening funds are tight. There is little confidence in entering the market to restock with standard-weight pigs. Leading pig companies in both northern and southern markets are still actively shipping pigs to replenish cash, highlighting the pattern of strong supply and weak demand!
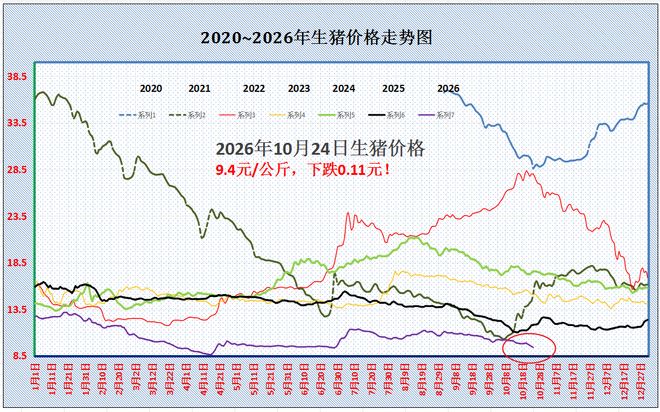
Citing institutional monitoring and analysis, as of 10 month 24, the national quote for standard-weight pigs of the three-way crossbreed had fallen to 9.4 yuan/kilogram, down 0.1 yuan/kilogram from the previous day. Hog prices continued to seek a bottom, down more than 20% year on year! Compared with the peak of 11.09 yuan/kilogram at the start of 9 month, the traditional “Golden September and Silver October” period has seen the hog market follow a “strong start, weak finish” pattern. Statistics show that hog prices fell by more than 15%, hitting a new low since the start of the second half of the year!
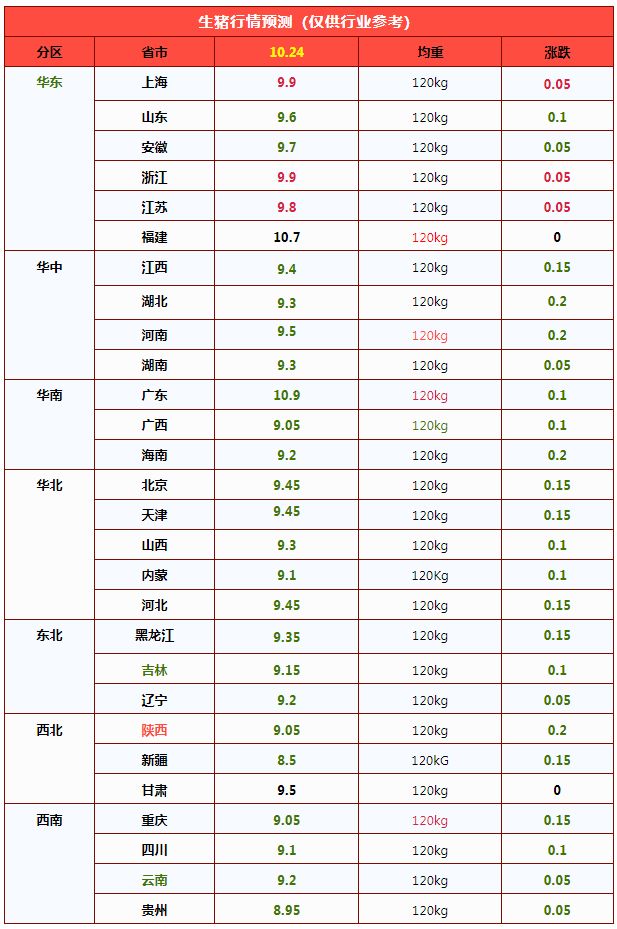
By region, across the north and south of China, among the 7 production areas and 28 provinces and municipalities covered by data monitoring, live hog quotes have generally declined, with the average price matching the level in Jiangxi. Quotes in Guizhou and Xinjiang fell below 9 yuan/kilogram, with Xinjiang bottoming out at 8.5 yuan/kilogram. Quotes in Fujian and Guangdong fell to 10.7 yuan and 10.9 yuan/kilogram, respectively. Live hog quotes across the north and south generally fell into the “9-yuan range,” and market fundamentals remained bearish!
Personally, I believe that because the supply-demand fundamentals are difficult to reverse, at the end of the month, producers remain highly motivated to bring hogs to market, while demand lacks marginal support. Over the next 1-2 days, hog prices are expected to continue sliding, and the average live hog price may fall further. However, I believe the “floor” for this price decline may hover around 9-9.2 yuan/jin, and the average live hog price is unlikely to have a basis for falling below 9 yuan/kg. Going forward, attention should be paid to changes in marginal demand and in the pace at which producers bring hogs to market!
It Won’t Stop! Hog Prices Fall “Viciously”—Will They Hit a “New Low” Next?
As 10月 draws to a close, the domestic live hog market has seen prices recover slightly from their lows early in the month, supported by the festive atmosphere, with quotes for standard hogs rising to 10.25 yuan/kg. However, this late-month rally in hog prices was short-lived. As the festive atmosphere faded, marginal support from demand weakened, while various types of producers on the supply side actively brought hogs to market. Prices came under pressure and fell, with the market seeing a “vicious” decline. As of now, 10月 is about to end, but hog prices have continued to fall, and the average price for standard hogs has repeatedly hit new lows for the second half of the year. So, will hog prices hit a new low for this year next? An analysis follows:
According to data cited from an industry organization, as of 10月24日, the national average ex-farm price for lean-meat-type crossbred hogs was 9.4 yuan/kg, equivalent to 4.7 yuan/jin, down 0.1 yuan/kg from yesterday and 20.61% year over year. Hog prices have retreated, and the market is seeing a “second bottoming-out.” The average live hog price has now fallen back to its level before the Dragon Boat Festival. The gap with the annual low of 8.63 yuan/kg is only 0.77 yuan/kg, and prices are falling more sharply than expected.
According to monitoring data, at present, among the 28 key regions monitored across northern and southern China and the 7 hog-producing regions, hog prices are continuing to fall in most areas, with only scattered quotes in East China showing a slight strengthening. The national average ex-farm price for live hogs is in line with the level in Jiangxi, with national quotes at 8.5-10.9 yuan/kg. In lower-priced areas, Xinjiang has bottomed out at 8.5 yuan/kg, while Guizhou quotes have fallen to 8.95 yuan/kg, and the average live hog price has dropped below 9 yuan/kg. In higher-priced areas, quotes have fallen to 10.9 yuan/kg in Guangdong and 10.7 yuan/kg in Fujian. Across the main markets in northern and southern China, live hog quotes have fallen to 9.05-9.9 yuan/kg, with prices generally entering the “4-yuan era”!
Currently, the decline in pig prices is “unstoppable,” and the market focus is gradually shifting lower. Prices have continued to trend downward in 10 month, falling by 8.29% compared with the start of the month. In my view, the reasons behind the downward pressure on pig prices are as follows:
First, supply is increasing while consumption is weak! As 10 month moves into its latter part, domestic hog supply this month has “increased rather than decreased” month on month. On the one hand, sow inventories 10 months ago increased month on month by 4 ten thousand head, supporting an increase in this month’s supply of market hogs. On the other hand, last month, demand received insufficient marginal support ahead of the Mid-Autumn Festival and National Day. Slaughterhouses reported that pre-holiday stockpiling fell short of expectations, and major integrated hog producers performed poorly in meeting their planned sales, with completion rates at 99.01%. Some production was carried over to later sales!
As a result, hog supply this month “increased rather than decreased.” In addition, sow inventories were previously at a high level, and production capacity efficiency was relatively high, further intensifying the pressure from this month’s oversupply. Moreover, domestic hogs have recently been gaining weight more quickly during fattening. As of this week, the market hog shipment weight had increased to 125.12 kilograms (Zhuochuang data), up 0.29% month on month, further strengthening the level of pork supply in the market!
However, on the demand side, demand has recently remained consistently sluggish. On the one hand, pork consumption has been insufficient, the boost from seasonal demand has been limited, and slaughterhouse operating rates have remained low, with the market absorbing hog supplies extremely slowly. On the other hand, as pork supply continues to strengthen, frozen pork is being released onto the market in succession. Expectations for ample pork supply in the fourth quarter are dampening the willingness of secondary fattening operators to enter the market and replenish stocks of standard-weight pigs, further intensifying the pressure from oversupply!
Secondly, with the arrival of the Frost's Descent solar term, temperatures are gradually falling in northern and southern regions, and cold air activity will become more frequent. Fattening pigs face increased stress risks, and large temperature fluctuations in some regions have led to more disease outbreaks at pig farms. This has further heightened panic among producers and accelerated changes in the pace of hog shipments!
Thirdly, the structure of hog inventories is changing. The number of medium and large hogs in domestic inventories has increased, and there is no significant price difference between standard-weight and heavyweight hogs. This limits the market's confidence in holding hogs back and also discourages secondary fattening from entering the market!
Based on this analysis, amid changes in supply and demand, hog prices continue to perform sluggishly, and the market may remain in a volatile downward trend in the short term! Going forward, watch for changes in shipments by large-scale hog companies and operating rates at slaughterhouses. If large-scale hog companies restrict sales and raise prices at the end of the month, the market may still have a chance to stop falling and recover! However, hog prices are unlikely to hit a new low, and prices are unlikely to fall below the previous low of 8.63 yuan/kg!