Key points:
-
French maize harvest expected to reach 7,04 Mt, according to AGPM
-
Lack of competitiveness of US wheat exports
-
Harvest pressure on maize in the United States
-
High soil moisture in the Southern Hemisphere
To find out everything about agricultural market news, click here
European wheat falls in the wake of Chicago
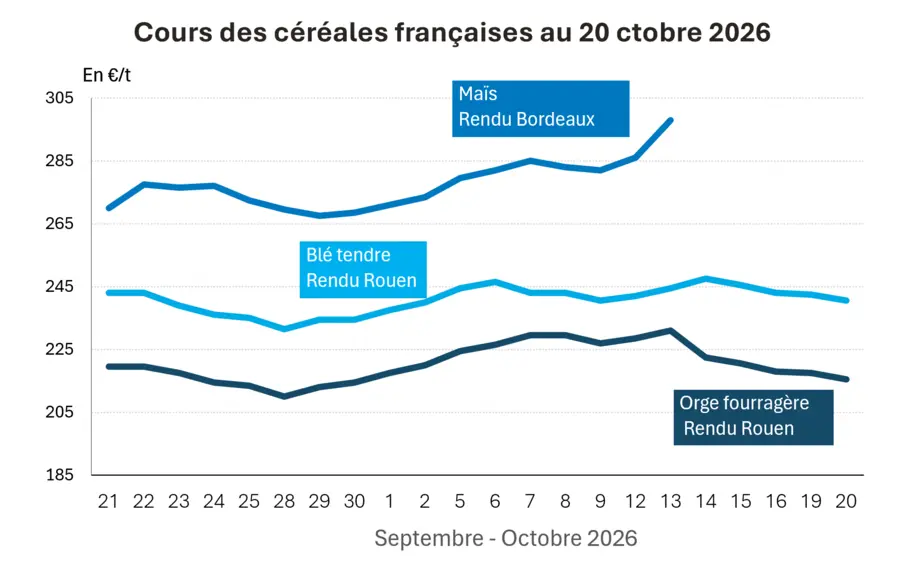
The wheat prices lost ground on Euronext between 19 and 20 October. They lost 2 €/t on the December contract to 241,50 €/t, and 2,75 €/t on the March and May contracts. The rain expected on theEuropean Union should allow the wheat harvests to proceed smoothly. The market has mainly moved in the shadow of the CBOT, where grain prices fell from one day to the next. The figures for European wheat exports, in line with those of last year, have failed to support prices. French wheat nevertheless enjoys relatively good export competitiveness. Cumulatively since the start of the season, however, it is the countries in the eastern European Union that are faring best, led by Romania, followed by Bulgaria, Latvia and Poland.
Dry sowing conditions and logistical tensions in the Black Sea region
In Russia and in Ukraine as well, the rains are expected to provide relief for sowing. 70 % of winter sowing had already been completed in Russia by 16 October, according to the Minister of Agriculture. This was while the conflict had eased somewhat yesterday. It is worth noting that a reorganization of rail freight approaching the port of Constanza was decided by Romanian officials. It should make it possible to eliminate the priority system and better define responsibilities in the event of delays. For Graintrade traders, this could indeed reduce the number of delays observed and increase the loading rate, provided the various stakeholders coordinate properly. Romanian rail traffic is facing many problems. According to Romanian grain market analyst Cesar Gheorghe (cited by Ukragroconsult), storage capacities limited in Romania (which he estimates at 16,5 Mt) turn grain wagons into “real silos on wheels”. Large-scale work on the tracks leading to the port of Constanza and a shortage of locomotives are delaying traffic. In addition, navigation on the Sulina Canal (the central branch of the Danube) is often interrupted due to weather conditions. According to ASAP Agri, navigation restrictions on the Danube limit the filling of barges.
European corn stands apart in light of France’s disastrous harvest
The corn price European are the only ones to end the day higher, gaining 2 €/t to 294,75 €/t for November, 1,75 €/t to 271,75 €/t for March, 2,25 €/t for June and 2,75 €/t for August. AGPM (General Association of Corn Producers) confirmed yesterday at a press conference that it expects a harvest around 7 Mt (7,04 Mt versus 13,7 Mt in 2025). Other operators are even below this figure. Concerns about French and European supplies have thus pushed prices up.
Wheat prices fall in the United States due to a lack of export competitiveness
Les wheat prices have lost ground on the futures marketsU.S. They lost 12 cents per bushel to 6,4325 $ per bushel on the CBOT December contract, 11,5 cents on March and 10 cents on May. The wheat exports from Uncle Sam’s country remain well behind the previous crop year. Wheat sowing and emergence remain slightly below the five-year average according to the USDA, but this is not worrying the markets. In the Southern Hemisphere, rainfall is starting to cause concern, after having improved soil moisture. The Buenos Aires Stock Exchange thus reports cereal-growing areas with excess water this week. Lachstock Consulting, for its part, reports that the rains are worrying Australian operators.
Decline in corn prices across the Atlantic
The drop in quotations for oil weighed on those of corn in Chicago, as did the harvest pressure. It is also estimated to be 44% complete by theUSDA versus 52% according to the five-year average. Consultant Michael Cordonnier also added 2 Mt to his forecast for Brazil's corn harvest, bringing it to 140 Mt, and left Argentina's unchanged atArgentina 60 Mt.
Fundamentals:
-
United States, winter wheat, planting: 63 % of intended acreage as of 18 October, compared with 51 % last week and a five-year average of 69 % (source: USDA)
-
United States, winter wheat, emergence: 39 % of planned acreage as of October 18 versus 27 % last week and 43 % on average over five years (source: USDA)
-
United States, corn, harvest: 44 % of acreage as of October 18 versus 33 % last week and 52 % on average over five years (source: USDA)
-
Brazil, corn, production: 140 Mt versus 138 Mt for the previous forecast (source: Soybean & Corn)
-
France, corn, production:7,04 Mt versus 13,7 Mt in 2025 (source: Arvalis and AGPM)
-
Ukraine, corn, harvest: 5,363 Mt, or 20 % of the area, with a yield of 58,8 q/ha (source: Ministry of Agriculture)
-
Ukraine, buckwheat, harvest: 57 300 t, or 95 % of the area, for a yield of 12,5 q/ha (source: Ministry of Agriculture)
-
Ukraine, millet, harvest: 88 100 t, or 94 % of the area, for a yield of 23 q/ha (source: Ministry of Agriculture)
International trade:
-
United States, wheat, exports: 240 300 t over the week of 8 to 15 October, or 7,22 Mt over 2026-2027, a decrease of -64,4 % compared with the previous campaign (source: USDA)
-
Ukraine, wheat, exports:3,377 Mt in 19/10 compared with 5,819 in 22/10/2025 (source: Ukrainian Customs)
-
Ukraine, barley, exports:473 t in 000 at 19/10 versus 1,026 Mt in 22/10/2025 (source: Ukrainian Customs)
-
Ukraine, corn, exports: 2,065 Mt in 19/10 compared with 1,271 in 22/10/2025 (source: Ukrainian Customs)
French physical market quotations of 20 October 2026 July basis for cereals
|
Soft wheat |
Specifications |
Deadline |
euro/t |
|
|---|---|---|---|---|
|
Dunkirk rendering |
220/11 miller Harvest 2026 |
Oct.–Dec. |
240,00 |
N |
|
Rendu La Pallice |
76/220/11 Harvest 2026 |
Oct.–Dec. |
244,00 |
N |
|
Rouen rendering |
76/220/11 Harvest 2026 |
Oct.–Dec. |
240,50 |
N |
|
Pontivy/Guingamp rendering |
forage 74 kg/hl base, 72 kg/hl mini Harvest 2026 |
Oct.–Dec. |
247,50 |
N |
|
Fob Moselle |
meunier Harvest 2026 |
Oct.–Dec. |
218,50 |
N |
|
Fob Rouen |
FCW Superior A2 class 1 majo. included Harvest 2026 |
Oct. |
inc. |
|
|
Fob La Pallice |
FAW Superior A2 class 1 increases included Harvest 2026 |
Oct. |
n.p. |
|
|
Marne Departure |
BPMF 220 Hagberg Harvest 2026 |
Oct.–Dec. |
230,50 |
N |
|
Departure Eure/Eure-et-Loir |
BPMF 76 kg/hl Harvest 2026 |
Oct.–Dec. |
232,50 |
N |
|
Southeast Departure |
meunier Harvest 2026 |
Oct.–Dec. |
249,50 |
N |
|
Corn |
Specifications |
Deadline |
euro/t |
|
|---|---|---|---|---|
|
Bordeaux finish |
Harvest 2026 |
Oct.–Dec. |
inc. |
|
|
Pontivy/Guingamp rendering |
Harvest 2026 |
Oct.–Dec. |
318,00 |
N |
|
Fob Bordeaux |
Harvest 2026 |
Oct.–Dec. |
Inc. |
|
|
Fob Rhin |
Harvest 2026 |
Oct.–Dec. |
271,50 |
N |
|
|
Harvest 2026 |
Jan.–June |
271,50 |
N |
|
Southeast Departure |
Harvest 2026 |
Oct.–Dec. |
inc. |
|
|
Durum wheat |
Specifications |
Deadline |
euro/t |
|
|---|---|---|---|---|
|
Port-la-Nouvelle rendering |
semolina standards Harvest 2026 |
Oct.–Dec. |
305,00 |
N |
|
Departure Eure/Eure-et-Loir |
seed standards Harvest 2026 |
Oct.–Dec. |
290,00 |
N |
|
Southeast Departure |
semolina standards Harvest 2026 |
Oct.–Dec. |
290,00 |
N |
|
Forage barley |
Specifications |
Deadline |
euro/t |
|
|---|---|---|---|---|
|
Rendu Rouen |
62-63 kg/hl Harvest 2026 |
Oct.-Dec. |
215,50 |
N |
|
Pontivy/Guingamp rendering |
Harvest 2026 |
Oct.–Dec. |
229,50-231,50 |
N |
|
Fob Moselle |
without limit. d'orgettes Harvest 2026 |
Oct.–Dec. |
201,50 |
N |
|
Departure Eure/Eure-et-Loir |
Harvest 2026 |
Oct.–Dec. |
207,50 |
N |
|
Southeast departure |
65-67 kg/hl Harvest 2026 |
Oct.-Dec. |
228,00 |
N |
|
Brewer's barley - Winter 6 rows |
Specifications |
Deadline |
euro/t |
|
|---|---|---|---|---|
|
Fob Creil |
Faro 11,5% max Port 500 t Harvest 2026 |
Jan.–June |
220,00-221,00 |
N |
|
Brewing barley - Spring |
Specifications |
Deadline |
euro/t |
|
|---|---|---|---|---|
|
Fob Creil |
Planet 11,5% max Port 500 t Harvest 2026 |
Jan.-June |
239,00 |
N |
|
Wheat bran from 13/10 |
Specifications |
Deadline |
euro/t |
|
|---|---|---|---|---|
|
Departure from Île-de-France |
Its fine soft wheat |
available. |
179,00-181,00 |
T |
|
|
Fine soft wheat bran pellets |
Available. |
199,00-201,00 |
T |
|
|
Semi-white remilling |
available. |
199,00-201,00 |
T |
|
|
Low-extraction soft wheat flour |
Available. |
204,00-206,00 |
T |
|
|
Durum wheat porridge |
available. |
204,00-206,00 |
T |
Dairy product trade quotations of 15 October 2026
|
Products |
Specifications |
Deadline |
euro/t |
|
|---|---|---|---|---|
|
Milk powder |
NBPL departure in 30 days 5% H BT bulk |
available. |
3275,00 |
N |
|
Whey powder |
NBPL departure in 30 days, BILA pH 6 bulk |
available. |
1650,00 |
T |
|
Buttermilk |
without a standard |
available. |
n.p. |
|
|
|
Dutch standards |
available. |
n.p. |
|
Rec.:Harvest; avail.:available; Inc.:incoté; N:Nominal; T:Treated; V:seller.
Dollar/euro exchange rate on 20 October 2026 |
|
Futures market quotes, 20 October 2026 |
||||||||||||||||||
|
|
bu. : bushel. |
European futures market close on 20 October 2026
|
|
|
||||||||||||||||||||||||
|
|
|
|
||||||||||||||||||||||||
|
|
|
|
||||||||||||||||||||||||
|
|
|
|
||||||||||||||||||||||||
International market quotations as of 20 October 2026
|
Energy/Sugar |
Deadline |
Closing value |
|---|---|---|
|
Oil (Nymex) |
Dec. 2026 |
97,82 $ |
|
London sugar |
Dec. 2026 |
547,10 $/t |
|
New York Sugar |
Mars 2027 |
20,52 cts/livre |
|
Maritime freight indices of 19 October |
|
|---|---|
|
Baltic Dry Index (BDI) |
2546 |
|
Baltic Panamax Index (BPI) |
2286 |
|
Baltic Capesize Index (BCI) |
3365 |
|
Baltic Supramax Index (BSI) |
1868 |
|
Baltic Handysize Index (BHSI) |
1016 |